Gig economy risk is easy to miss when the arrangement is described mainly in terms of flexibility.
You choose when to work. You can take another client. And you may avoid an office, a fixed schedule, or a long commute. In the right kind of independent work, that freedom is real and valuable.
But something else happens at the same time.
Many of the risks that an employer once absorbed can move onto your side of the arrangement.
If demand drops, your income may drop with it. Get sick, and the time off may be unpaid. Or if the work requires equipment, software, insurance, transportation, or workspace, some or all of those costs may become yours. Retirement saving may require deliberate action instead of payroll automation. Taxes may need to be estimated and reserved rather than quietly withheld.
None of that makes independent work bad.
It means flexibility has a balance sheet.
And if you never build that balance sheet, a work arrangement that looks profitable at the top line can feel very different after the risk is priced in.
The useful question is not whether gig work is good or bad. It is which risks moved to you, whether you are being paid enough to carry them, and whether you have enough buffer to survive when one of them becomes real.
Gig Economy Risk Is Really About Risk Transfer
Every work arrangement allocates risk somewhere.
In a traditional employment relationship, the organization usually carries a meaningful share of operating risk. It has to find customers, finance the business, maintain systems, manage payroll, absorb some periods of weaker demand, and provide whatever compensation and benefits are attached to the job.
The worker carries risks too, of course. Employment is never guaranteed. Jobs disappear, companies fail, benefits vary, and wages may not keep pace with costs.
Still, a lot of infrastructure sits around the employee before the paycheck arrives.
Independent work changes that architecture.
You may gain more control over schedule, clients, geography, methods, or workload. In exchange, more responsibility can move outward from the organization and inward toward you.
That Trade Can Be Worth It
This is where most commentary gets too ideological.
The Bureau of Labor Statistics counted 11.9 million people whose sole or main job was independent contracting in July 2023. Importantly, 80.3 percent of those independent contractors said they preferred that arrangement rather than a traditional one.
That matters.
People are not always being dragged into flexibility against their will. Some actively choose it because the autonomy is worth more to them than the structure they are giving up.
But preference does not erase economics.
A good independent arrangement works because the freedom is valuable enough, the compensation is strong enough, or the worker has built enough infrastructure to carry the transferred risk.
A weak arrangement gives the worker the risk without enough control, pricing power, or buffer in return.
Seven Risks Hidden Inside Flexible Work
Gig economy risk becomes easier to understand when you stop treating it as one problem.
There are several different risks inside the arrangement, and they behave differently.
1. Income Volatility
An employee may know roughly what will arrive each pay period.
An independent worker may know what they earned last month.
Those are not the same thing.
Client demand changes. Projects end. Platforms get crowded. Seasonal work slows down. A large customer delays payment. A strong month can be followed by a weak one without anything being “wrong” with the business.
That means the worker carries more variance.
Variance is manageable when you expect it.
It becomes dangerous when your household budget is built as though every good month will repeat.
2. Unpaid Downtime
Independent workers often think in billable hours.
Life does not.
You still spend time quoting work, answering messages, doing bookkeeping, scheduling, maintaining equipment, learning systems, marketing, chasing invoices, and finding the next customer.
Then there is downtime you did not choose.
You get sick. A child gets sick. A client cancels. The platform is slow. The car needs repair. The project ends early.
If none of those hours generate income, they still belong in the economics of the work.
3. Benefits Replacement
Traditional jobs vary widely in benefits, so there is no universal package to compare against.
Still, the difference can be substantial.
BLS found that workers in contingent jobs were much less likely to receive employer-provided health insurance than workers in noncontingent jobs. Among the alternative work arrangements it measured, employer-provided coverage also varied significantly.
Independent contractors are different again because most are self-employed.
The practical lesson is not that every gig worker lacks health coverage. Many obtain coverage through a spouse, the individual market, government programs, or another source.
The issue is who has to arrange and finance it.
When a benefit leaves the work arrangement, the cost does not necessarily disappear.
4. Tax and Administrative Risk
A paycheck can make taxes nearly invisible.
Independent work makes them harder to ignore.
Self-employed workers may have income-tax obligations, self-employment tax obligations, recordkeeping needs, deductible business expenses, and estimated-tax responsibilities depending on their situation.
The IRS maintains an entire Small Business and Self-Employed Tax Center for a reason.
This is not merely paperwork.
If you treat every dollar deposited into your account as spendable income, tax season can expose a cash-flow problem that was building all year.
A better system separates money before lifestyle gets a vote.
5. Asset Risk
Some forms of independent work are asset-light.
A consultant may need a laptop, software, and professional insurance.
Other work consumes physical assets aggressively.
Vehicles accumulate miles. Tools wear out. Equipment breaks. Phones get replaced. Supplies get used. Home-office costs do not vanish because nobody sends you an invoice for the room.
Gross revenue hides depreciation well.
Your bank account eventually does not.
6. Platform or Client Concentration Risk
A person can technically be self-employed while economically depending on one source of work.
That is a fragile structure.
If one client represents 80 percent of your income, that client has enormous influence over your economic life even if you are legally independent.
The same problem can appear with a platform.
A change in fees, ranking, eligibility, demand, rules, or access can alter your income without changing your underlying skill at all.
The issue is concentration.
One source of demand is convenient.
One source of demand is also one point of failure.
7. Long-Term Career Capital Risk
This risk is quieter.
You can make money for years without building much that becomes more valuable over time.
Some independent work builds extraordinary career capital. You develop specialized expertise, customer relationships, pricing power, a portfolio, intellectual property, reputation, and systems you own.
Other work produces income but little accumulation.
The task repeats. The platform owns the customer relationship. Your rate barely moves. The work provides no credible path toward a stronger adjacent capability.
That does not make the work worthless.
But income and career capital are different assets.
Gross Flexibility Is Not the Same as Net Flexibility
“Set your own hours” sounds like a complete statement.
It is not.
You may be free to work whenever you want, but the best-paying demand may occur at specific times. Free to take a week off? Only if you can afford seven days without revenue. Free to reject a client? Not if that client represents half your income. And free to leave a platform, but only if you have another way to reach customers.
That is the difference between gross flexibility and net flexibility.
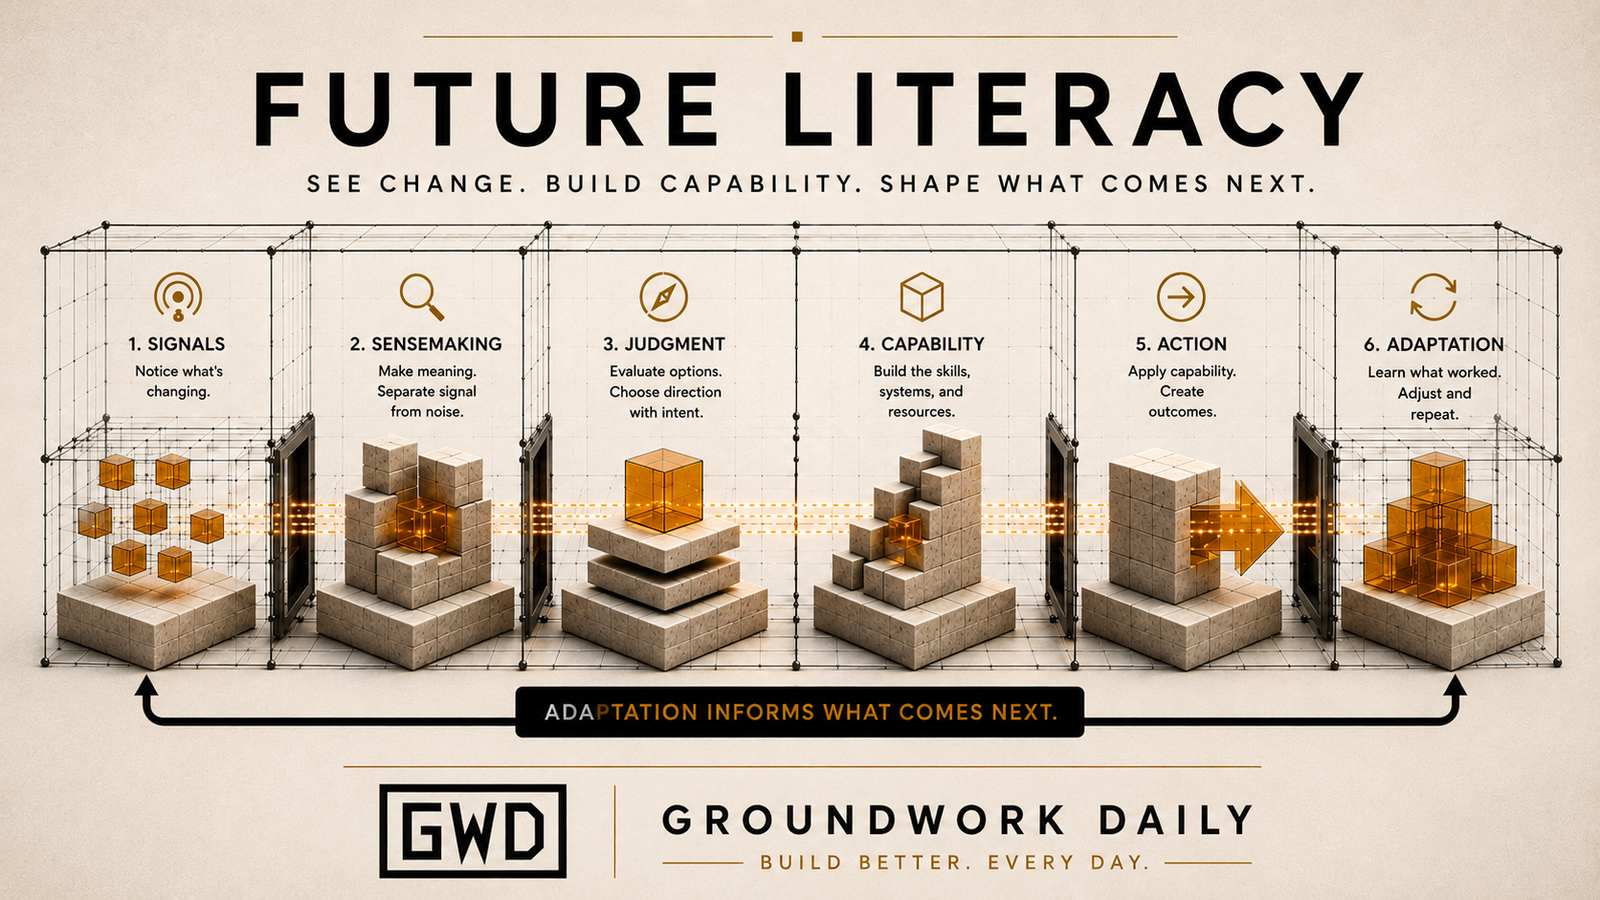
Future Literacy Framework
Gross Flexibility vs. Net Flexibility
Gross flexibility is the freedom the work arrangement appears to give you.
Net flexibility is the freedom that remains after income needs, fixed expenses, client concentration, unpaid time, and risk are accounted for.
This distinction changes how you evaluate a job.
Schedule autonomy is real.
But autonomy without financial room can become theoretical freedom.
Calculate the Rate You Are Actually Earning
The cleanest way to misunderstand independent work is to compare gross hourly revenue with an employee’s hourly wage.
The numbers are measuring different things.
Suppose a contractor bills $50 an hour.
That sounds clearly better than a $35-per-hour employee role.
Maybe it is.
But first ask what the $50 has to cover.
How many hours are actually billable?
What does health coverage cost?
What do software, equipment, licenses, fuel, maintenance, insurance, and professional services cost?
How much time is spent finding work?
How much needs to be reserved for taxes?
What happens during vacation or illness?
What are you contributing toward retirement?
Now you are comparing systems rather than headline rates.
Use a True-Rate Calculation
A Better Independent-Work Calculation
Start with: Gross revenue
Subtract: Business operating costs
Subtract: Benefits you must replace yourself
Reserve: Taxes based on your actual situation
Reserve: Equipment replacement and maintenance
Reserve: Unpaid time off and downtime
Reserve: Long-term savings or retirement
Then divide by: All hours required to operate the work, not just the hours a customer sees.
This number will not be perfect.
It will be more useful than pretending gross revenue is take-home pay.
Build a Gig Economy Risk Transfer Ledger
If you are considering independent work, or already depend on it, write down what moved.
Do not keep the arrangement in your head as one vague idea called “flexibility.”
Break it apart.
| Risk | Who Carries It? | My Buffer | Weak Point |
|---|---|---|---|
| Income volatility | Worker / client mix | Cash reserve | One slow month hurts immediately |
| Health / downtime | Mostly worker | Insurance + runway | No paid time off |
| Taxes | Worker | Dedicated tax reserve | Revenue mistaken for spendable cash |
| Equipment | Worker | Replacement fund | Breakdown stops income |
| Demand concentration | Worker | Multiple clients / channels | One platform controls access |
| Retirement | Worker | Automated contribution | Nothing happens by default |
Your ledger will look different.
That is the point.
A freelance designer, construction contractor, rideshare driver, consultant, therapist, photographer, software developer, and part-time marketplace seller may all be called independent workers while carrying very different economics.
“Gig economy” is a broad label.
Your actual risk profile is what matters.
When Gig Work Is Structurally Strong
Independent work can be an excellent economic arrangement.
In fact, some of the strongest career structures are built outside traditional employment.
But strong independent work usually has certain properties.
You Have Pricing Power
If you can raise your rate because your expertise has become more valuable, you have leverage.
If the platform, marketplace, or client effectively sets the price and you have little room to negotiate, you have less.
You Have More Than One Source of Demand
Several clients are not automatically safer than one employer.
However, diversified demand reduces the damage one lost customer can cause.
The strongest version goes further.
You own at least part of the relationship with the people who buy your work.
Your Work Builds Something That Compounds
You gain reputation.
Your portfolio improves.
Your operating systems become better.
Referrals grow.
Your expertise deepens.
You create reusable intellectual property, processes, customer relationships, or assets.
In that structure, today’s work can make tomorrow’s work easier to win or more valuable to sell.
Your Fixed Costs Are Reasonable
A high-income independent business with low operating costs has very different economics from work that requires expensive equipment, heavy vehicle use, or continuous paid access to a platform.
The more capital the work consumes, the more carefully you need to price replacement and maintenance.
You Have Buffers
This may be the biggest difference between freedom and fragility.
A strong buffer lets you reject a bad client. It lets you survive a slow month, recover from illness without panic, and replace broken equipment without financing an emergency. It also lets you wait for a better opportunity instead of accepting the first one available.
Cash is not the only buffer.
Skills, relationships, insurance, diversified demand, portable evidence, and low fixed expenses all create room to move.
When Flexibility Becomes Dependency
Independent work becomes structurally weak when the worker carries most of the downside without gaining meaningful control over the upside.
You may technically choose your schedule, but you cannot choose your price. Technically you may have many customers, but one platform controls access to all of them. You might technically be able to stop working, but missing three days would put rent at risk. And you may technically be self-employed, but one client determines nearly all of your income.
That is not fake flexibility.
It is constrained flexibility.
Watch for Single Points of Failure
Ask what could damage your income quickly.
One client? A single platform? One vehicle? A particular credential? One piece of equipment? Your own ability to work every day?
The more your livelihood depends on one thing continuing to function, the more attention that dependency deserves.
Build the Buffers Before the Risk Arrives
You cannot remove all gig economy risk.
You can make the structure less brittle.
Separate Tax Money Early
Do not rely on whatever happens to remain in checking when taxes are due.
Use a separate reserve and base the amount on your tax situation and professional guidance where needed.
Price Unpaid Work Into Paid Work
Your clients may never pay an invoice labeled “bookkeeping.”
They still have to fund the business that does the bookkeeping.
The same is true for business development, equipment replacement, software, training, insurance, and administration.
Your rate has to carry the whole system.
Automate Long-Term Saving
Traditional payroll systems often make retirement saving easier because contributions can happen automatically.
Independent workers may need to build that automation themselves.
The exact account or contribution strategy depends on personal circumstances, but the operating principle is simple: if long-term saving happens only when a month feels unusually good, it can remain optional forever.
Diversify Before You Are Desperate
The worst time to find another client is the week after your only client leaves.
The worst time to learn another demand channel is the day a platform changes access.
Build the second connection while the first one still works.
Keep Building Portable Capability
Do not let the work become a loop that produces cash but no stronger future position.
Ask what you know now that you did not know a year ago.
What evidence have you created, and what adjacent work can you now perform?
What customer problem can you solve at a higher level?
Those questions turn independent work into career capital rather than only transactions.
A Quarterly Independent-Work Audit
You do not need to analyze your business every day.
Once a quarter, though, take an hour and look at the structure.
Check Your Revenue Concentration
What percentage came from your largest client, platform, or channel?
If that source disappeared, how long would it take to replace?
Check Your True Rate
Include nonbillable hours and real operating costs.
Has the economics improved, held steady, or deteriorated?
Check Your Buffers
Can you absorb a weak month?
Could you replace critical equipment?
Are taxes reserved?
Is long-term saving happening?
Check Your Career Capital
What became more valuable this quarter besides your bank balance?
Did you gain a skill, relationship, system, reputation, asset, or body of evidence that makes future work stronger?
Check Your Freedom
This is the overlooked question.
Do you have more ability to choose than you did a year ago?
Can you reject worse work?
Raise prices?
Change platforms?
Take time off?
Move toward better customers?
If revenue has increased while your practical freedom has decreased, the business may be growing in the wrong direction.
Worker Classification Is a Different Question
There is one distinction worth making before closing.
The economics of independent work and the legal classification of a worker are not the same question.
A person cannot simply be called an independent contractor and automatically become one under every applicable law.
Federal and state rules can differ, and classification standards can change. Misclassification can affect wage protections and other rights.
So use the Risk Transfer Ledger to understand your economics.
Use qualified legal or tax guidance when the question is your actual status or obligations.
Do not confuse a business label with a legal conclusion.
The Groundwork: Know Who Holds the Risk
The gig economy did not invent economic risk.
It made some forms of risk easier to move.
That can produce genuinely better work arrangements. It can give people control over schedule, geography, clients, methods, and income opportunities that a conventional job might never provide.
It can also create arrangements where the worker inherits volatility, administrative burden, equipment costs, downtime, benefits replacement, and long-term responsibility without enough compensation or control to carry them safely.
The label does not tell you which one you have.
The structure does.
So stop evaluating independent work only by the hourly rate or the freedom to log on whenever you want.
Look underneath.
Who carries the volatility, and who funds the downtime? Who replaces the equipment, or owns the customer relationship? And who saves for the future? What happens when the main source of demand disappears?
And most importantly, are you building enough leverage and buffer that the freedom becomes more real over time?
A flexible arrangement is strongest when you can see the risk, price the risk, diversify the risk, and afford to carry it.
Further Groundwork
The Portable Skill Problem: Why Your Expertise Doesn’t Always Travel
Test whether your work is building capability that remains valuable outside one employer, client, platform, or industry.
How to Read a Job Market Before the Layoffs Start
Learn how to spot hiring contraction, demand pressure, role consolidation, and other labor-market signals while you still have room to move.
The Credential Gap Is Closing. The Capability Gap Is Widening.
See why current application, evidence, and judgment increasingly matter alongside formal qualifications.
What Learning Actually Requires After 30
Build a learning system that fits limited time and converts new knowledge into usable capability.
Receipts
U.S. Bureau of Labor Statistics · Contingent and Alternative Employment Arrangements
Federal data on contingent jobs, independent contractors, worker preferences, earnings, and health-insurance coverage across different work arrangements.
U.S. Government Accountability Office · Work Arrangements
Federal review of nonstandard work arrangements, worker outcomes, access to benefits, and limitations in national labor-force data.
Internal Revenue Service · Small Business and Self-Employed Tax Center
Official tax resources for self-employed workers and small businesses, including self-employment taxes, reporting, forms, and business tax obligations.
U.S. Department of Labor · Employee Misclassification
Federal guidance explaining why employee and independent-contractor classification matters for wage and workplace protections.