
Money Monday — The Value of Dirty Hands
The value of hard work and discipline is more than labor — it’s leverage. Skill and structure turn effort into equity, proving freedom belongs to those who build and repair with their own hands.
Economy & Ownership examines how income becomes stability, how assets become leverage, and how economic systems distribute cost, control, risk, and opportunity.
Money matters, but money alone does not explain economic power. A paycheck can disappear. An asset can become a liability. A strong economic headline can coexist with household pressure. A community can generate enormous spending while owning very little of what that spending supports.
This category follows the structure underneath those outcomes: cash flow, financial discipline, ownership, debt, labor, inflation, prices, markets, housing, consumer behavior, community capital, economic signals, institutional incentives, and the systems that determine who keeps the value after the transaction is over.
The Economy & Ownership Principle
Income creates movement. Ownership determines what remains.
Discipline directs resources. Margin creates options. Ownership creates control. Strong economic systems connect all three instead of mistaking earnings, spending, or access for durable financial power.
Economic questions become easier to navigate once you identify which layer you are actually dealing with: household structure, the broader economy, ownership, or the power behind price.
Household Structure
Build financial discipline around allocation, cash flow, debt, savings, ownership, risk, and the everyday systems that turn income into stability.
Economic Interpretation
Follow inflation, spending, labor, corporate behavior, consumer pressure, and economic incentives beyond the headline number.
Data & Accountability
Read public economic data with context, separating what a number measures from what people assume the number means.
Ownership & Market Power
Trace prices back to property, supply chains, lending, distribution, ownership, and the structures that determine who captures value.
Marcus Vaughn builds Money Monday around the practical architecture of financial control.
The series examines allocation, spending, debt, saving, emergency reserves, financial boundaries, household systems, skill value, economic optionality, ownership, lifestyle inflation, and the habits that determine whether income becomes leverage or simply moves through the household.
Money Monday does not begin with investment products or wealth aesthetics. It begins with governance. What comes in? Where does it go? What is protected? What is leaking? Which obligations create fragility? What decisions increase control?
The objective is not to make money the center of life. It is to build enough structure that money stops destabilizing everything around it.
Begin with financial structure
The First Paycheck Lesson: Income Means Nothing Without Allocation
Discipline Before Dollars is one of the foundational frameworks underneath Economy & Ownership.
The principle is simple: more money does not automatically repair a weak financial system. Without allocation, boundaries, tracking, maintenance, and clear priorities, additional income can simply expand consumption, obligations, and exposure.
Structure has to arrive early enough to govern growth.
That applies to a first paycheck, a raise, a household budget, a business, an investment pool, or a community ownership system. Capital works better when rules arrive before pressure.
Structure → Margin → Options → Ownership → Stability
Modern life offers enormous access.
People can rent housing, lease transportation, use digital platforms, borrow money, subscribe to services, participate in marketplaces, and gain temporary use of assets they do not control.
Access can be useful. It is not ownership.
The Ownership Equation asks four harder questions: Who controls the asset? Who sets the terms? Who captures the upside? Who carries the risk?
Ownership therefore should not be confused with simply acquiring more things. An owned asset with unsustainable debt, poor maintenance, weak documentation, or no productive value can still create fragility.
The stronger standard is disciplined ownership: control that can be sustained, improved, protected, and eventually transferred.
Ownership Framework
The Ownership Equation: Why Control Matters More Than Access
Trent “Numbers” Lawson builds Economy Commentary around the distance between economic reporting and economic experience.
Inflation may decline while prices remain high. Employment can grow while specific households remain exposed. Consumer spending can remain resilient while people quietly reduce frequency, trade down, or rely more heavily on credit. Asset values can rise while wages fail to keep pace.
None of those conditions makes the headline number false. It means the number needs interpretation.
Economy Commentary examines costs, incentives, ownership, consumer behavior, corporate responses, labor, inflation, housing, markets, and the places economic pressure moves when conditions change.
The method is consistent: check the number, identify the mechanism, follow the pressure, and say what the evidence supports.
Walter Cook builds The Analyst’s Ledger around economic accountability and disciplined interpretation of public data.
GDP revisions, inflation reports, unemployment data, wages, consumer sentiment, housing metrics, credit conditions, and productivity figures can all be useful. They can also be misunderstood when context disappears.
Walter’s work starts before the argument. What exactly is being measured? Which population is represented? What period is being compared? What is excluded? Does the aggregate number hide important variation underneath?
The purpose is not distrust of numbers. It is better literacy around what numbers can and cannot prove.
Every price sits inside a structure.
Samuel Drayton builds Power & Price around the relationship between spending, ownership, markets, property, supply chains, capital, distribution, and economic control.
Consumers usually encounter the economy at the register. They see the price and decide whether to buy. Power & Price continues past that moment.
Who owns the property? Who controls distribution? Who financed the transaction? Who owns the brand? Who receives rent? Where does the margin go? Which asset keeps producing value after the purchase is complete?
Spending changes hands. Ownership determines what keeps collecting.
Ownership does not have to be built alone.
Groundwork Daily’s group economics work examines cooperative ownership, investment clubs, shared capital, community land, lending circles, neighborhood finance, worker ownership, pooled risk, governance, and the operating rules required when multiple people try to build something together.
The strongest lesson is not that collective ownership is automatically superior. It is that shared capital magnifies whatever structure already exists.
Good intentions without governance create conflict. Clear purpose, contribution rules, records, voting systems, exit provisions, and accountability make collective ownership more durable.
A community can produce income and still remain economically weak if value leaves faster than local systems can retain it.
The category therefore examines local banking, community capitalism, capital circulation, small business ownership, lending, CDFIs, anchor institutions, cooperative systems, and the difference between economic activity and economic control.
Spending locally can matter, but spending alone is not enough. Durable community wealth requires pathways that convert income into businesses, land, housing, tools, institutions, and assets that remain after the transaction.
Economic power is rarely created through one transaction.
Work produces income. Discipline directs income. Margin absorbs pressure. Margin also creates options. Options make ownership easier to pursue without desperation. Ownership creates claims on assets, cash flow, appreciation, productive capacity, or future value.
Maintenance protects what has been built. Transfer allows the value to survive beyond the original builder.
The category follows that progression:
earn → direct → stabilize → build margin → acquire → control → maintain → transfer.
Use this map to move from the economic question to the Groundwork Daily framework designed to examine it.
| Question | Series or Framework | What It Helps You See |
|---|---|---|
| Why does my income keep disappearing? |
Money Monday | Allocation, cash flow, spending, saving, debt, household systems |
| Why doesn’t more money automatically create stability? |
Discipline Before Dollars | Structure, rules, financial governance, sequencing |
| What is the difference between access and ownership? |
The Ownership Equation | Assets, control, leverage, obligations, transfer |
| What is happening beneath the economic headline? |
Economy Commentary | Incentives, costs, household pressure, consumer behavior |
| What does this economic statistic actually tell me? |
The Analyst’s Ledger | Data interpretation, measurement, context, economic accountability |
| Who captures value after I spend? |
Power & Price | Property, markets, supply chains, ownership, price, distribution |
| How can people build ownership together? |
Group Economics | Shared capital, governance, cooperative ownership, pooled risk |
Economy & Ownership is built around practical questions about money, ownership, wealth, inflation, economic systems, financial discipline, markets, household stability, and long-term control.
How do I build financial stability?
Why am I still broke even when I earn money?
What is the difference between income and wealth?
Why does ownership matter?
Is renting the same as lacking financial progress?
How does inflation affect households?
Why do prices stay high after inflation falls?
What does GDP actually measure?
How should I read economic data?
How does group economics work?
Why do cooperative ownership systems fail?
How can communities keep more wealth local?
The category uses distinct builders because household financial structure, economic interpretation, public data, and ownership power require different analytical lenses.
Money Monday
Financial discipline, ownership, allocation, household structure, economic optionality, generational continuity, and the systems that turn income into stability.
Trent “Numbers” Lawson
Economy Commentary
Inflation, consumer behavior, labor, markets, corporate incentives, household pressure, costs, ownership, and economic interpretation.
The Analyst’s Ledger
Economic data, inflation, GDP, labor, wages, housing, credit, infrastructure cost, public accountability, and structural interpretation.
Samuel Drayton
Power & Price
Spending, property, ownership, supply chains, pricing power, distribution, capital, markets, and where economic value ultimately accumulates.
Economic life encourages people to measure progress through visible consumption.
The larger home, newer vehicle, higher salary, premium subscription, business revenue, market rally, or rising asset price can all look like proof.
Sometimes they are. Sometimes they are only movement.
Economy & Ownership asks what remains after the motion stops. Is there margin? Is debt manageable? Is the asset controlled? Does the system survive pressure? Can the value be retained? Can it be transferred? Who still gets paid after everyone else finishes working?
Those questions move the conversation from money as appearance to economic position as infrastructure.
Continue Building
Start with the economic layer you need to understand, then move deeper into the system beneath it.
→ Financial Structure:
Money Monday
→ Operating Principle:
Discipline Before Dollars
→ Ownership:
The Ownership Equation
→ Economic Interpretation:
Economy Commentary
→ Economic Data:
The Analyst’s Ledger
→ Ownership & Market Power:
Power & Price
Build more than income.
Groundwork Daily examines money, ownership, inflation, economic systems, household stability, financial discipline, markets, shared capital, and the structures that turn resources into lasting control.
The value of hard work and discipline is more than labor — it’s leverage. Skill and structure turn effort into equity, proving freedom belongs to those who build and repair with their own hands.
Economic headlines shape belief. Arithmetic reveals constraint. The Analyst’s Ledger explains what the numbers actually mean beneath the narrative.
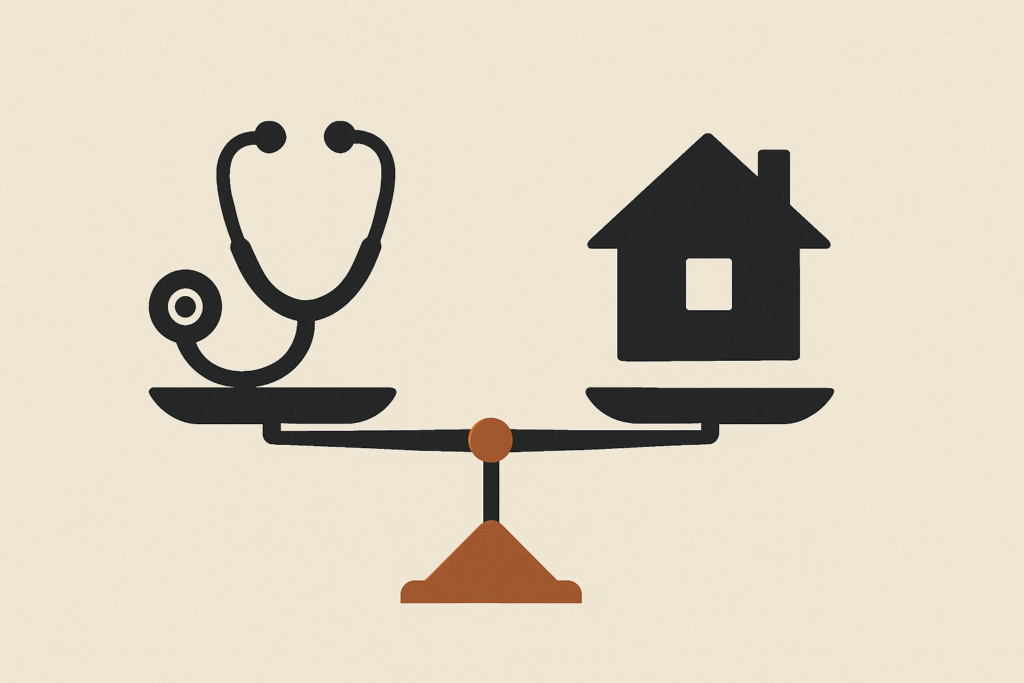
Male nurses economic impact is bigger than culture talk. It is labor math. When men enter nursing, staffing stabilizes, overtime drops, and households gain a durable income lane.

Power and price are inseparable. Every system that looks stable is being paid for by someone else—often quietly, often later.
The Black dollar is powerful when it moves with intention. Strategic spending creates leverage, strengthens community infrastructure, and reshapes how corporations respond.
Homeownership without habit becomes a liability. Marcus Vaughn breaks down why financial discipline must come before the dream of ownership.
Avoidance feels neutral until the bill arrives. Disorder isn’t free. It quietly taxes time, attention, and money until the system collapses under its own neglect.
Dual-income life is not a flex; it is a framework. When two salaries move in rhythm instead of rivalry, stability stops being an accident and becomes a strategy. DINK life isn’t about luxury. It is about leverage—turning shared math into shared momentum.
People sell rental income like it’s a shortcut to freedom, but most “passive” plays turn into unpaid jobs with a mortgage attached. This Money Monday breaks down why stability comes from structure first, not stress disguised as income.
Households are feeling the strain of unstable systems. When public signals become unreliable, protection starts with structure. This is the math that keeps a home steady.

Buying at the peak turns a dream into a debt sentence. This Money Monday breaks down single homeownership risks—and why timing, structure, and shared accountability protect your freedom.

Financial ownership and accountability are built through structure, maintenance, and disciplined decision-making. Learn how systems, habits, and planning determine what you can truly keep.