☰ Contents
Group economics is not a shortcut around discipline. It is discipline organized at scale.
That distinction matters because pooling money is the easy part. Building a system people can still trust when money, pressure, disagreement, and opportunity enter the room is much harder.
What Group Economics Actually Means
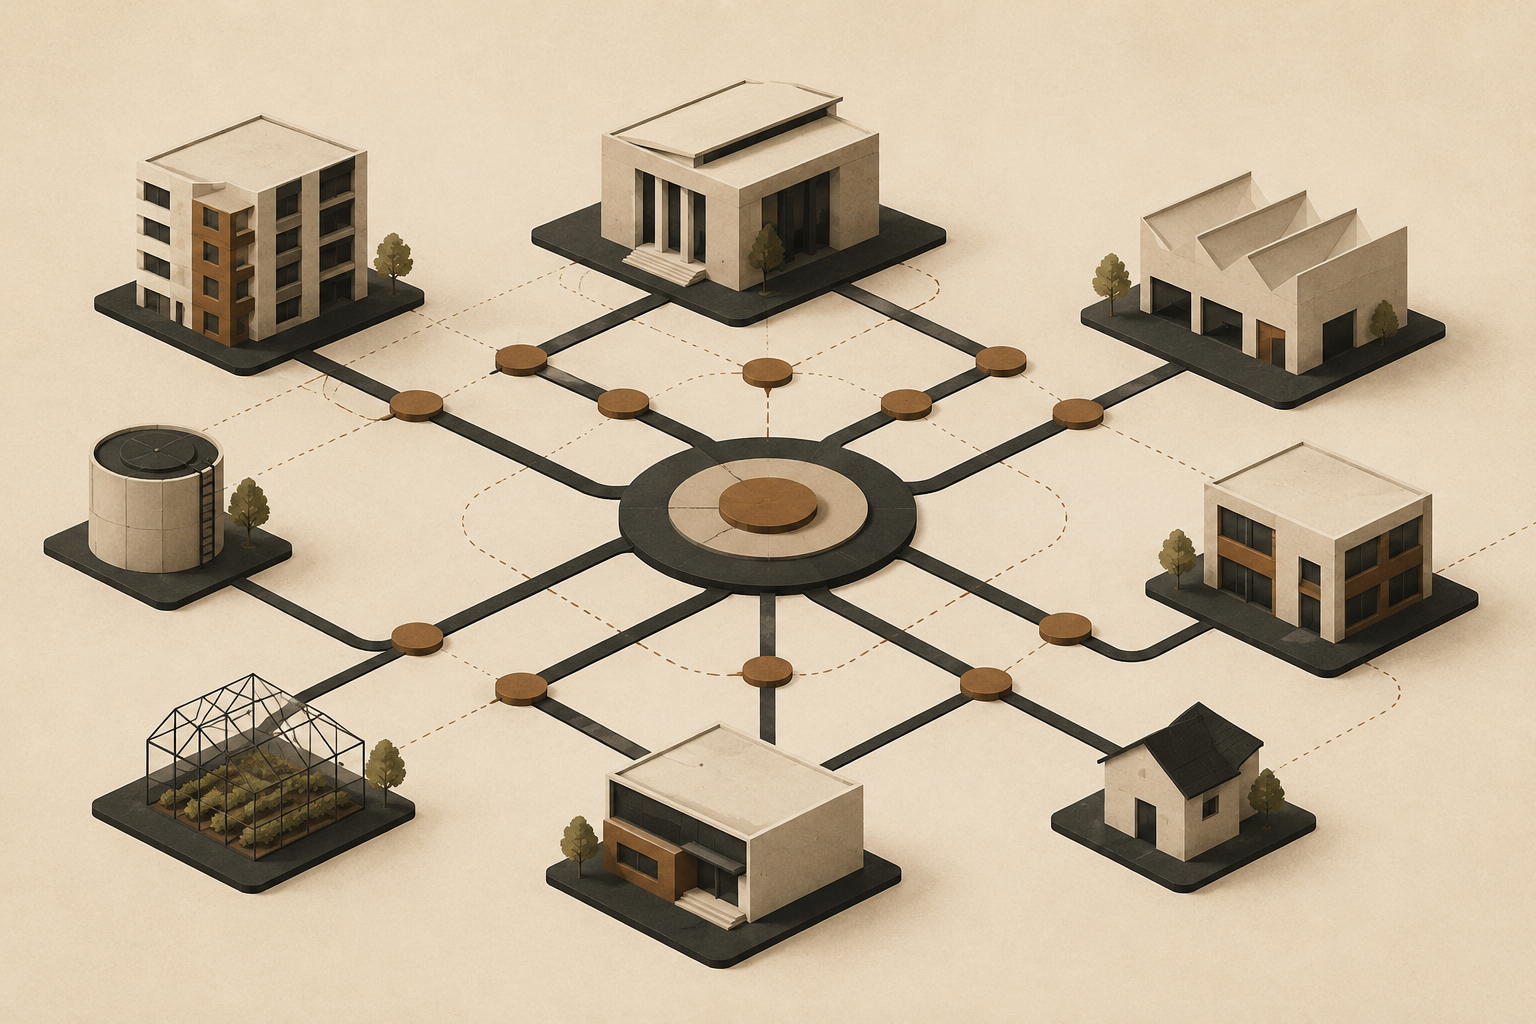
Group economics is re-emerging as a practical ownership strategy. Investment clubs, cooperative housing, community land trusts, worker-owned businesses, credit unions, and shared investment structures all begin with a similar idea: some forms of ownership become easier when people coordinate capital instead of carrying the entire burden alone.
That does not make collective ownership automatically wise. In fact, putting several people into a weak system can multiply dysfunction faster than it multiplies wealth.
Still, the underlying logic is powerful.
For decades, American economic culture has emphasized individual hustle, personal achievement, and self-reliance as primary routes to mobility. Those strategies can work. However, they also leave households carrying enormous costs individually.
Housing is expensive. Starting a business requires capital. Childcare can consume a major share of household income. Emergencies arrive without permission. Meanwhile, access to affordable credit and appreciating assets remains uneven.
Under those conditions, coordination becomes more attractive.
Group economics turns scattered resources into shared capacity. Done well, it can help people buy assets, spread risk, build enterprises, and create forms of stability that would be difficult to reach alone.
Why Group Economics Is Returning
The idea is not new.
Families and communities have pooled resources for generations. Mutual aid societies, rotating savings clubs, cooperative farms, burial societies, credit unions, investment circles, and informal family lending systems all reflect versions of the same economic instinct.
Many of these systems emerged because established institutions did not serve everyone equally. Black communities, immigrant communities, working-class families, and other groups often built parallel financial structures when conventional banking, lending, insurance, or investment channels remained unavailable or hostile.
Necessity created coordination.
Today, technology can reduce some of the friction. Digital bookkeeping, shared documents, automated payments, electronic voting, accounting platforms, and online financial tools make it easier to coordinate contributions and preserve records.
Yet technology does not solve the central problem.
People still need rules.
They still need to know who owns what, who decides what, what happens when someone misses a payment, and how a member leaves without destroying the entire structure.
Therefore, the principle has not changed. The tools have.
Economic Conditions Are Making Cooperation More Relevant
Group economics becomes more attractive when the cost of doing everything alone rises.
For many households, that is exactly what has happened. Housing costs demand substantial capital. Small businesses need financing before they generate dependable revenue. Childcare and transportation strain household budgets. At the same time, debt can delay saving and investment.
Consequently, shared participation can create leverage where isolated effort reaches a ceiling.
The cooperative economy already includes businesses and institutions across agriculture, finance, housing, utilities, retail, and worker ownership. Organizations such as the National Cooperative Business Association continue to support and document that broader cooperative ecosystem.
At the household and neighborhood level, the same logic can appear in smaller forms:
- Families pooling capital toward property ownership
- Investment groups purchasing assets together
- Worker-owned businesses sharing ownership and governance
- Rotating savings groups helping members reach capital targets
- Cooperative housing reducing individual ownership burdens
- Shared childcare or transportation arrangements lowering recurring costs
The important distinction is leverage.
Cooperation should increase capacity. If the structure merely redistributes confusion, it has failed before the money has had a chance to work.
Discipline Before Dollars.
Capital magnifies the system underneath it. Therefore, shared money should never arrive before shared rules. Build the structure first. Then give the structure something valuable to carry.
How Modern Group Economics Actually Works
The strongest shared ownership systems usually begin with a narrow objective.
That matters. A group does not need to build an entire alternative economy on day one. It may simply need to solve one problem together.
Perhaps five people want to build an investment pool. Several families may want to acquire property. Workers may want to buy an existing business. A neighborhood group may need an emergency fund with defined contribution and distribution rules.
Smaller scope makes accountability easier to see.
This is the argument behind small-scale group economics. Cooperation becomes more durable when the objective is specific, participation is manageable, and everyone understands what the system is designed to do.
Modern structures can include:
- Shared down-payment strategies
- Community-owned commercial property
- Investment clubs
- Worker-owned service businesses
- Community-supported agriculture
- Cooperative housing
- Neighborhood emergency funds
Each model has different legal, tax, financial, and governance requirements. As a result, informal trust should never substitute for appropriate professional advice when meaningful money or property is involved.
Still, the structural questions remain remarkably consistent.
Who contributes? Who owns? Who decides? Who carries risk? Who keeps the records? What happens when someone wants out?
For a deeper look at those mechanics, see Group Economics: How Shared Ownership Actually Works.
Why Group Economics Fails
This is where romantic thinking has to end.
Good intentions are not governance.
A group can contain trustworthy people and still create an untrustworthy system. Friendship does not define voting rights. Family ties do not establish an exit mechanism. Shared values do not reconcile a disputed ledger.
Problems usually appear when the system encounters pressure.
One person contributes late. Another person wants to sell. Someone believes effort should count more than capital. A member needs emergency access to money that was supposed to remain invested. Two people disagree about expansion.
Suddenly, the group discovers that everyone had been operating from a different unwritten agreement.
Durable group economics needs written rules for:
- Contribution requirements
- Ownership percentages
- Voting and decision rights
- Financial reporting
- Conflict resolution
- Missed obligations
- Leadership responsibilities
- Member removal
- Voluntary exit
- Asset liquidation or transfer
Otherwise, every disagreement becomes personal.
That is expensive.
Why Group Economics Fails examines these failure points more closely. The lesson is simple: shared ownership without governance is optimism with a bank account.
What Successful Group Economics Does Differently
Successful cooperative systems do not eliminate disagreement. Instead, they create a structure capable of surviving it.
Mondragon in Spain offers one large-scale example. Its network of cooperatives has operated across manufacturing, finance, retail, education, and other sectors for decades.
The value of the example is not that every community should copy Mondragon. Scale, law, history, industry, and local conditions matter too much for that.
Instead, the lesson is structural. Shared ownership needs institutions around it.
Likewise, smaller credit unions, housing cooperatives, worker cooperatives, savings circles, community land trusts, and investment groups survive when participation is matched by governance.
Collective ownership works best when discipline scales alongside participation.
In other words, adding people should not weaken the rules. Growth should force the rules to become clearer.
Group Economics Is About More Than Money
The deeper value of group economics is resilience.
A well-built system can spread risk across several participants. It can preserve knowledge when one person leaves. In addition, it can circulate opportunity through a family, business, or community rather than allowing every generation to start from zero.
That is where shared economics becomes infrastructure.
People learn how to govern assets together. Records accumulate. Relationships with financial institutions develop. Younger members can observe how ownership works. Meanwhile, the system builds institutional memory.
Over time, the asset may matter less than the capacity created around it.
However, none of that happens automatically.
Durability still depends on standards, documentation, financial transparency, dispute processes, and continuity planning.
For that reason, Group Economics Governance belongs at the center of this cluster rather than at its edge.
The Group Economics Operating Framework
Before money moves, a serious group should be able to answer five questions in writing.
Those questions look basic. That is exactly why skipping them is dangerous.
Most groups want to discuss returns before discussing exits. They want to imagine the property before defining control. They talk about what everyone can gain before deciding how the group will handle loss.
Reverse the order.
Design for pressure first.
If the system can survive disappointment, disagreement, delay, and departure, it has a better chance of surviving success.
What to Watch Next in Group Economics
The next phase will probably look less like a grand movement and more like thousands of smaller ownership experiments.
Watch areas such as:
- Community land trusts
- Cooperative and shared housing
- Worker ownership and employee buyouts
- Local investment networks
- Family investment structures
- Shared infrastructure cooperatives
- Community-owned commercial property
- Digital tools for cooperative administration
Still, technology will not be the decisive innovation.
Governance will.
The strongest systems will make ownership easier to understand, contributions easier to track, decisions easier to audit, and exits less destructive.
That may not sound revolutionary.
Good infrastructure rarely does.
Where to Start With Group Economics
Do not begin by collecting money.
First, identify one problem that coordinated resources could realistically solve. It might involve housing, transportation, business capital, education, childcare, emergency savings, or investment.
Next, identify the smallest viable group.
Then write the rules before anyone contributes a dollar.
Define the purpose. Set the contribution schedule. Establish decision rights. Decide how records will be maintained. Finally, establish what happens when someone leaves.
Professional legal, tax, or financial guidance may also be necessary depending on the structure and assets involved.
The objective is not to make the arrangement complicated.
It is to make expectations visible.
The Groundwork: Ownership Needs Structure
Group economics does not eliminate individual responsibility. It demands more of it.
Once money becomes shared, your choices no longer belong only to you. Other people’s capital, time, trust, and opportunity enter the structure.
That changes the standard.
The question is no longer whether everyone means well. The question becomes whether the system can carry people through changing circumstances without collapsing into confusion.
Strong communities have always understood some version of this truth. Survival rarely depends on independence alone. It also depends on relationships sturdy enough to coordinate resources when individual capacity reaches its limit.
However, cooperation without accountability is fragile.
Ownership without records is fragile.
Trust without rules is fragile.
Therefore, the real work begins before the first investment.
Build the container.
Then build the capital.
That is the deeper logic behind Discipline Before Dollars. Money does not become stability simply because we possess it. Stability emerges when capital enters a system capable of directing, protecting, and preserving it.
Further Groundwork
Continue through the Groundwork Daily ownership architecture:
Receipts
For additional research on cooperative ownership and operating models: