
Credit scoring systems turn financial information into signals that can influence whether credit is offered, on what terms, and at what price. By the time a lender makes a decision, data from consumer reports, application information, internal records, scoring models, underwriting rules, or other permitted sources may already have shaped the available path.
That process can feel almost invisible. A number appears. An approval arrives. A limit is set. An application is denied. Yet the visible outcome is usually the end of a longer decision structure.
The important question is not whether scores exist. The sharper question is how data becomes access, who governs the model, and what happens when the information or decision is wrong.
Credit scoring systems are useful precisely because they compress large amounts of information into a form that can support repeatable decisions. However, compression always leaves something out.
That makes governance, explanation, accuracy, and correction part of the system—not administrative extras added afterward.
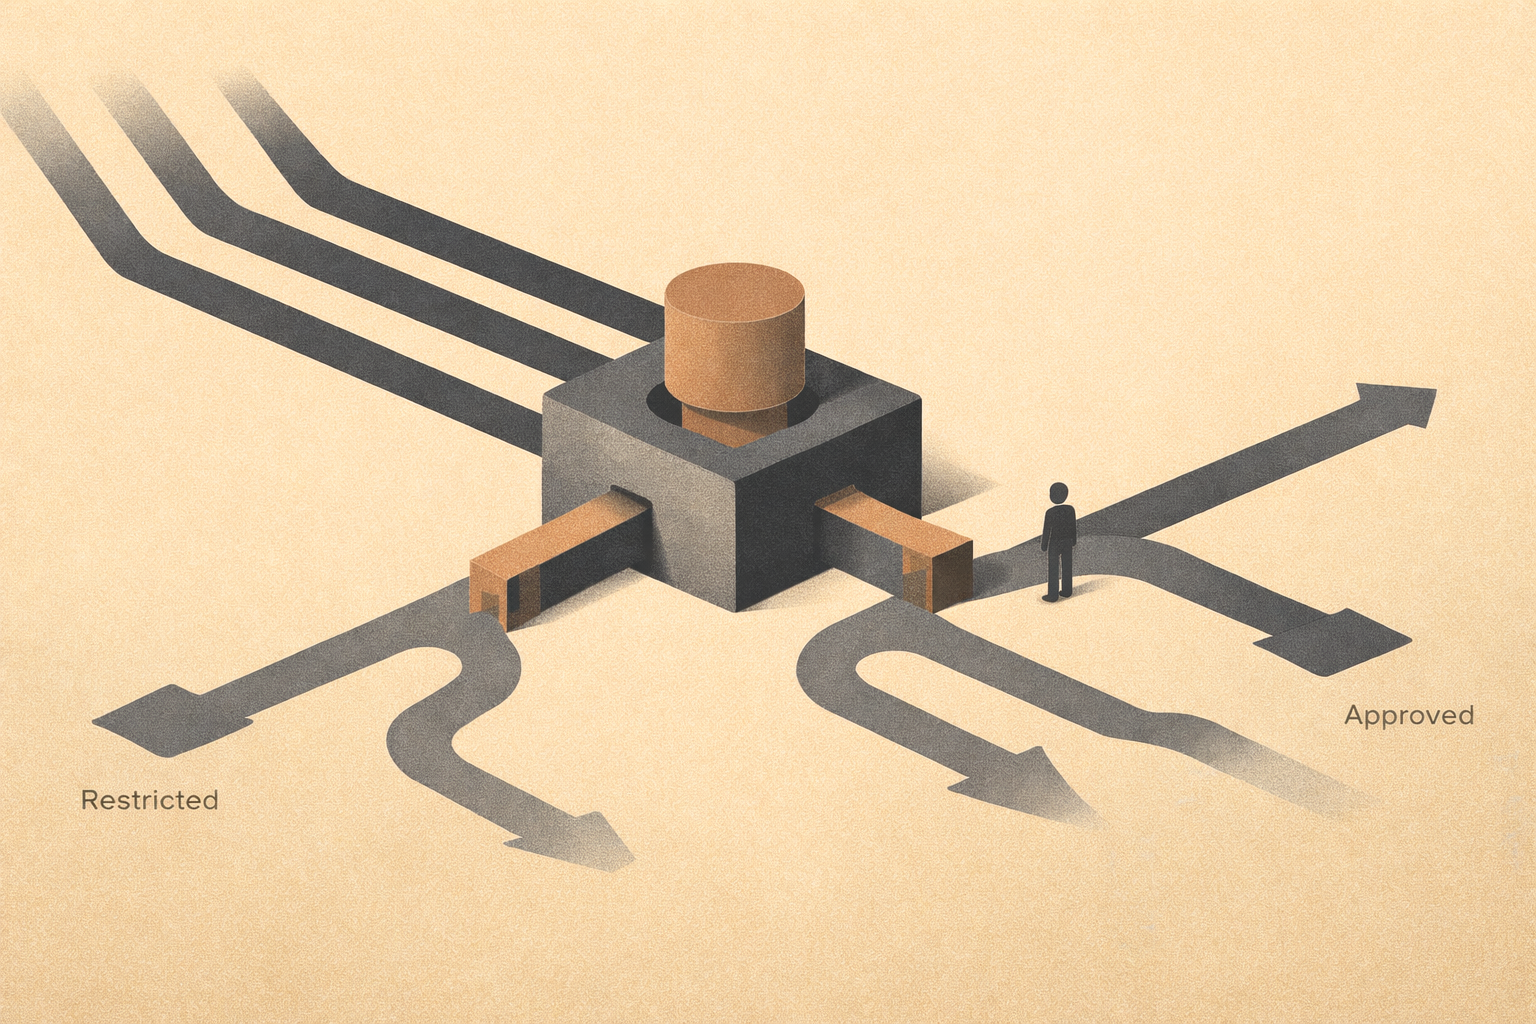
Credit Scoring Systems Sit Inside a Larger Decision Pipeline
A credit score is only one possible input into a lending decision. Lenders can also consider application information, income, debt, collateral, internal account history, fraud controls, underwriting policies, and other factors permitted for the product and decision.
Therefore, the cleanest way to understand credit decision systems is to separate the pipeline into functions.
Stage 01
Data
Consumer reports, application information, account history, and other permitted inputs enter the decision process.
Stage 02
Scoring
A scoring or risk model converts selected information into an estimate, classification, score, or other decision signal.
Stage 03
Policy
Lender thresholds, product rules, pricing structures, and underwriting criteria determine how those signals affect available options.
Stage 04
Accountability
The institution remains responsible for compliant use, explanations where required, data correction pathways, and appropriate model governance.
The distinction matters because a score does not approve or deny credit by itself in every system. Instead, it may become one input inside a broader decision rule.
A number becomes powerful when an institution decides what the number is allowed to control.
Credit Scoring Systems Begin With Data Quality
Before a score can influence access, information has to enter the system. For traditional credit scoring, that information often comes from consumer reports maintained by credit reporting companies, although the exact data and decision process vary by model and lender.
This is the first place where structural accuracy matters.
Bad Inputs Do Not Become Good Decisions
A sophisticated model cannot repair incorrect underlying information simply by processing it more consistently.
If an account is reported inaccurately, a balance is wrong, an identity issue contaminates a file, or another material record is incorrect, downstream decisions can reflect that error.
That is why the Fair Credit Reporting Act places duties around the accuracy and handling of consumer-report information and gives consumers mechanisms to dispute inaccurate or incomplete information.
Not Every Score Uses the Same Formula
People often talk about “the credit score” as though one universal number governs the entire market. In reality, multiple scoring models and versions exist, and lenders may use different models for different purposes.
Likewise, the factors influencing one score should not automatically be treated as the formula for every credit decision.
The practical lesson is simple: understand the distinction between the consumer report, the score generated from information, and the lender’s final decision structure.
A Credit Score Compresses Information Into a Signal
Scoring exists because raw financial information can be difficult to evaluate consistently at scale. A model reduces part of that complexity by estimating risk through a defined quantitative structure.
That compression can improve speed and consistency. Yet the score remains a model output, not a complete biography of the borrower.
Models Are Simplifications by Design
Financial models represent relationships among selected characteristics, values, and events. They depend on assumptions and therefore have limitations.
Updated 2026 interagency guidance on model risk management emphasizes that models can create adverse consequences when they are incorrect or misused and calls for risk-based model development, validation, monitoring, governance, and controls.
That is the structural point. A model can be useful without being complete.
Precision Should Not Be Confused With Certainty
A numerical result can feel more objective because it is specific. However, specificity does not erase uncertainty, model limits, data quality problems, or policy choices surrounding the output.
The number is only one part of the architecture. Institutions still decide how that number enters underwriting, pricing, account review, or other credit decisions.
Credit Scoring Systems Influence Access Through Policy
The score becomes consequential when it interacts with lender policy.
A threshold may influence whether an application moves forward. Another rule may affect pricing, credit limits, or the level of documentation required. Internal models may also be used alongside external credit scores or other risk measures.
The Model and the Policy Are Not the Same Thing
This distinction is easy to miss.
The model generates an output. The institution decides how that output is used.
Consequently, two lenders can interpret similar credit information differently because their products, risk tolerances, underwriting rules, or broader decision structures differ.
Access Can Be Shaped Without a Dramatic Denial
Credit decisions are not limited to a simple yes or no.
Consumers may receive different limits, interest rates, pricing, collateral requirements, or other terms depending on the product and decision process.
Federal risk-based pricing rules recognize this distinction. In covered situations, consumers may receive notices when information in a consumer report contributes to materially less favorable credit terms.
Human Review Is Not the Only Form of Accountability
A weak critique of automated credit decisions assumes that every important decision should simply be handed to a person.
That is not automatically better.
Human reviewers can also be inconsistent, biased, overloaded, or constrained by policy. Moreover, some credit products are intentionally designed for highly standardized decision processes.
The Better Question Is Whether the Decision Is Governed
Meaningful control can include model validation, monitoring, documented decision rules, adverse-action explanations, quality controls, dispute rights, escalation pathways, and human review where the institution determines it is appropriate or legally required.
In other words, accountability should not be reduced to whether somebody manually reads the file.
Human Discretion Still Needs Authority
Where human review does exist, the role should be clear. A reviewer needs to know what can be reconsidered, what is fixed by policy, what evidence can change the decision, and how exceptions are handled.
A “human in the loop” label means little if the person can only confirm what the system has already made irreversible.
Where Credit Scoring Systems Can Fail Quietly
The most consequential failures do not necessarily look like a broken website or obviously absurd score. Many appear as ordinary decisions built on weak inputs, weak governance, or poor use of an otherwise functional model.
Risk 01
Incorrect Data
Inaccurate or incomplete information in a consumer report can influence scores and downstream credit decisions until the information is corrected.
Risk 02
Model Misuse
A model can become unreliable when it is used outside the purpose, population, assumptions, or conditions for which it was designed.
Risk 03
Rigid Policy
A lender can turn a useful score into an overly blunt gate if thresholds or decision rules are applied without appropriate governance.
Risk 04
Diffuse Responsibility
Accountability weakens when the lender points to the bureau, the bureau points to furnished data, and the consumer cannot tell which part of the pipeline produced the problem.
Clean Process Does Not Guarantee Correct Outcome
A system can execute every step exactly as designed and still produce an outcome based on inaccurate data or an inappropriate use of a model.
Therefore, operational consistency is not enough. The decision structure also needs mechanisms for checking accuracy, monitoring model performance, and correcting mistakes.
Contestability Is Part of Credit-System Accountability
One of the strongest safeguards in any consequential decision system is the ability to challenge bad information or understand why an adverse outcome occurred.
Credit law provides concrete examples of this principle.
Consumers Can Dispute Credit-Report Information
Under the Fair Credit Reporting Act, consumer reporting companies and furnishers have obligations related to disputed information. Consumers can challenge information they believe is inaccurate or incomplete.
This matters structurally because the correction path reaches upstream. Instead of merely appealing the final score, the consumer can challenge information feeding the system.
Adverse Actions Require Explanation
When a lender takes adverse action based on information in a consumer report, federal law requires notice to the consumer. Depending on the circumstances, the notice includes information about the consumer reporting company, dispute rights, and, when a credit score was used, the score and key factors affecting it.
That does not make the entire credit system transparent. Still, it creates something important: a decision cannot simply disappear behind “the algorithm.”
Groundwork control rule: a consequential system becomes more accountable when people can identify the input, understand the adverse outcome, and challenge information that is wrong.
How to Read Your Position in the Credit System
Consumers do not control the lender’s model, but they can improve their visibility into the information surrounding the decision.
Review the Underlying Report
A credit score is downstream from information. If something looks wrong, the first question should be whether the underlying consumer-report information is accurate.
Read Adverse-Action Notices Carefully
A denial or other covered adverse action is not merely a rejection letter. It can contain information that helps identify which credit-report source or score contributed to the decision and what steps are available next.
Separate Score Improvement From Error Correction
These are different problems.
Accurate negative information is not the same as an error. If the information is correct, the strategy may involve improving the underlying financial pattern over time. If the information is inaccurate, the appropriate move is to use the dispute process rather than trying to “optimize” around bad data.
Do Not Treat One Score as Your Financial Identity
A credit score is a risk signal generated for a particular use. It can materially affect access, but it is not a complete measure of financial capability, personal worth, or future potential.
The Credit Scoring Systems Control Test
A disciplined credit decision architecture should be able to answer questions beyond whether the model produces a number.
Groundwork Credit Control Test
-
What information enters the decision?
Separate consumer-report data, application information, internal data, scores, and other permitted inputs. -
What does the model actually estimate?
A score should have a defined purpose rather than being treated as a universal measure of creditworthiness. -
How does policy use the output?
Thresholds, pricing, limits, and underwriting rules should be distinguished from the model itself. -
How is performance monitored?
Institutions need controls appropriate to the model’s risk, use, complexity, and potential consequences. -
What happens when information is wrong?
Correction and dispute pathways must reach the data feeding the decision. -
Can the consumer understand an adverse outcome?
Required notices and reasons should make the decision more legible rather than hiding it behind a score. -
Who owns the decision?
Responsibility should remain attached to the institution using the model and making the credit determination.
If those questions have no clear answer, the system may be efficient without being adequately governed.
Credit Scoring Systems Belong Inside the Structure of Control
Credit scoring is a useful case study because it makes the Tech as Discipline framework concrete.
Data enters. A model interprets part of it. Policy converts the output into possible action. Institutions then remain responsible for how the structure is used.
That sequence maps directly onto The Structure of Control: Automation, AI, and Human Authority .
Execution Can Be Automated
Data retrieval, calculations, routing, notifications, and other defined processes can operate at scale.
Models Can Support Judgment
Scores and risk models can make large decision environments more manageable by producing consistent quantitative signals.
Authority Still Belongs to the Institution
The organization chooses the model, product rules, thresholds, governance structure, vendor relationships, monitoring process, and treatment of exceptions.
Technology does not erase that ownership.
Further Groundwork
→ The Structure of Control: Automation, AI, and Human Authority
→ When Systems Make Decisions for You
The Groundwork: Access Needs an Appeal Path
Credit scoring systems turn complexity into a manageable signal. That is their value.
Their danger appears when the signal is treated as the whole person, the whole decision, or an authority nobody can question.
A disciplined system separates the layers. Data should be accurate. Models should be used for purposes they can reasonably support. Policy should define how much authority the output receives. Governance should monitor whether the structure still performs as intended.
When something goes wrong, the person affected needs a way to identify the problem and challenge inaccurate information or understand the adverse decision.
That is not an inconvenience around the system. It is part of what makes the system accountable.
Measure risk. Govern the model. Explain the consequence. Preserve a path to correction.
Groundwork Architecture
What Holds Credit Decision Systems Together
Credit systems become durable when quantitative models can support repeatable decisions without separating power from explanation, correction, and responsibility.
Primary Core Principle
Build What Holds
Build What Holds asks whether a decision structure remains reliable after scale, model limits, data errors, changing conditions, and exceptions begin applying pressure.
A credit system should not depend on perfect data or assume that one model remains appropriate forever. Monitoring, validation, governance, and correction are part of the architecture.
What the Principle Requires Here
The system must be able to detect weakness before ordinary model use turns that weakness into repeated decisions.
A model that cannot be questioned, monitored, or corrected does not truly hold.
Primary Condition · Owns
Accountability
Accountability keeps responsibility attached to the institution using the score, model, underwriting policy, or consumer report.
A bureau may supply information. A vendor may supply a model. Software may automate the workflow. Even so, the organization taking the credit action must remain able to explain and govern its role in the decision.
Contestability Makes Accountability Visible
Dispute rights, adverse-action notices, correction processes, governance controls, and clear institutional ownership give the system a way to confront error rather than simply repeat it.
Accountability becomes real when a consequential output has an identifiable owner and a usable correction path.
Supporting Conditions: Discernment helps institutions distinguish a useful quantitative signal from a complete judgment, while Boundaries determine what authority a model or score should receive inside the final decision.
Explore the Groundwork Daily Core Principles and Conditions Architecture .
Receipts
- Federal Trade Commission. The Fair Credit Reporting Act establishes protections concerning the accuracy, fairness, privacy, permissible use, and dispute of information maintained by consumer reporting agencies. Review the Fair Credit Reporting Act .
- Federal Trade Commission. FTC guidance explains adverse-action and risk-based-pricing notice obligations when consumer reports and credit scores contribute to covered credit decisions. Review guidance on credit decisions and adverse action .
- Consumer Financial Protection Bureau. CFPB guidance explains consumer rights when a credit application is denied based on credit-report information, including notice of principal reasons and access to information about the score used in relevant circumstances. Review CFPB guidance on denied credit applications .
- Office of the Comptroller of the Currency, Federal Reserve, and FDIC. Updated 2026 interagency model risk management guidance addresses model development and use, validation, monitoring, governance, controls, and third-party products through a risk-based approach. Review the 2026 model risk management guidance .