
The Analyst’s Ledger · Federal Funding Model
A reparations proposal becomes a fiscal system when eligibility, benefits, timing, financing, and administration are defined. The model below does not determine whether reparations should be adopted or what a remedy should be worth. It shows what must be specified before a national proposal can be evaluated as federal policy.
The Funding Question
What a Reparations Cost Funding Model Has to Define
Before any headline total becomes useful, the proposal has to specify the rules that produce it. First comes eligibility. Next comes benefit design. Then timing determines how the obligation moves across years. Financing determines how federal resources are raised or committed. Finally, administration determines whether the program can verify claims, distribute benefits, resolve disputes, and maintain controls.
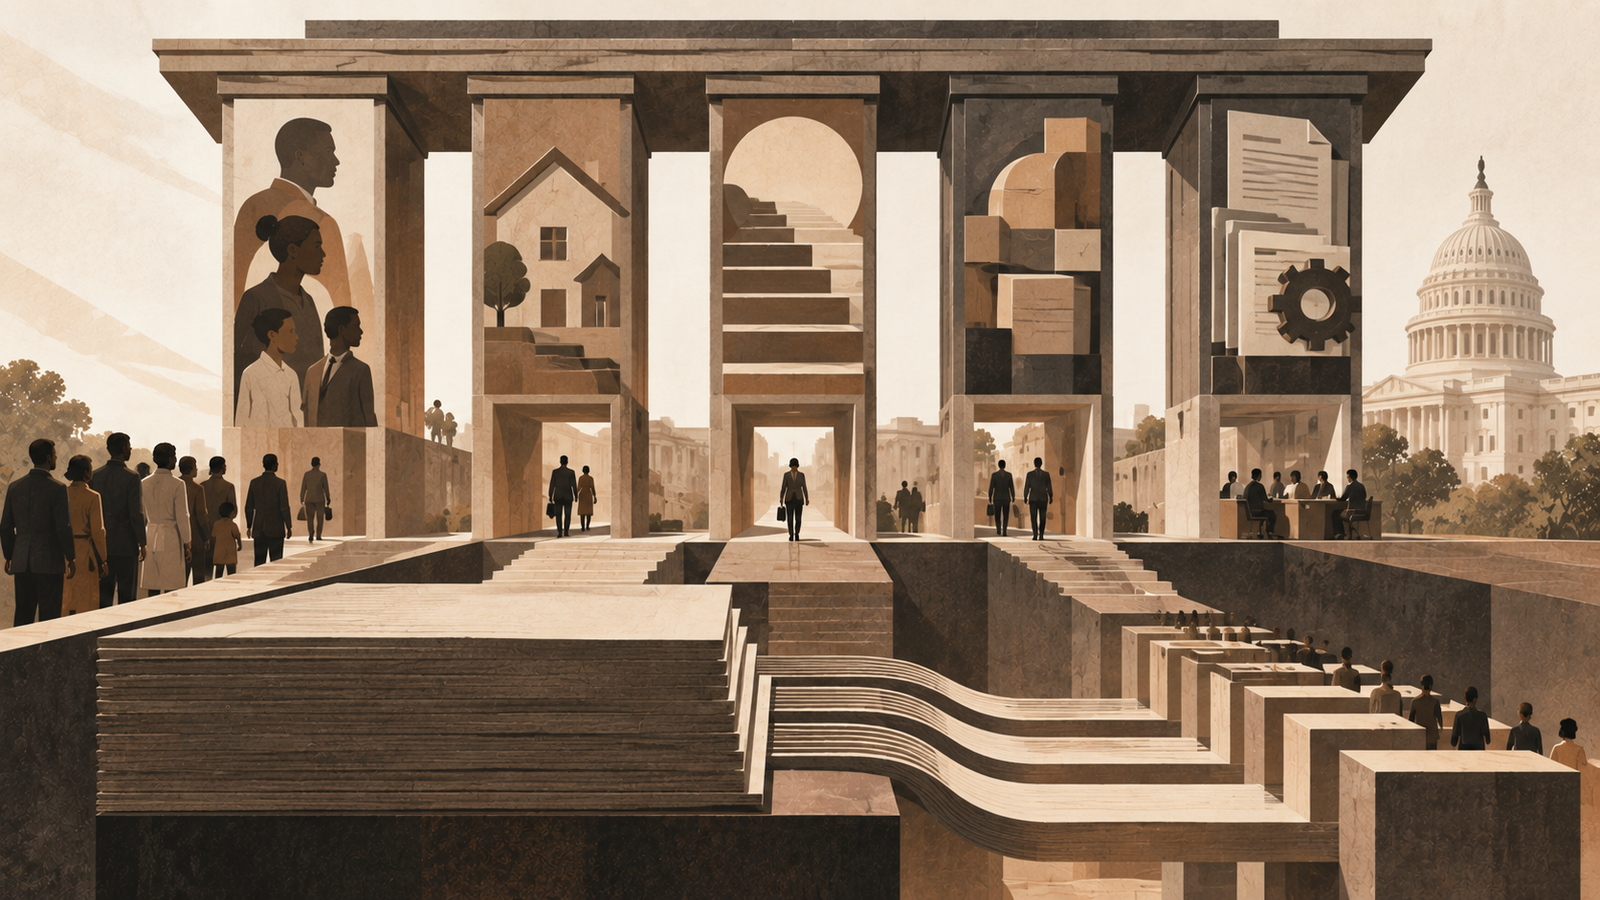
The Analyst’s Ledger Model
How to Read the Numbers
The scenarios in this article are illustrative sensitivity tests. They are not recommendations, not estimates of what reparations should cost, and not a conclusion about whether a reparations program should be enacted.
Why the Headline Number Is Not Enough
A reparations cost funding model has to answer a harder question than “How much would reparations cost?” The headline number matters. But it is only the beginning.
A federal program would also need to define who qualifies, how benefits are calculated, when money is distributed, how the program is financed, and what institution carries the administrative load.
As a result, changing any one of those variables changes the fiscal picture with it.
That is why a $500 billion program, a $2 trillion program, and a $3.75 trillion program cannot be understood from their price tags alone. Total cost is not the same as annual cost. Financing is not the same as spending. Borrowing is not free money. A trust fund does not eliminate the need for capitalization. And none of these models works without an administrative system capable of determining who receives what.
The numbers do not settle the reparations debate. They do something more useful.
They tell us what the debate would have to become before a national proposal could function as policy.
Start With Five Variables, Not One Number
Most reparations cost estimates begin with multiplication. First, define an eligible population. Next, assign an average benefit. Then multiply the two.
That calculation produces a gross program cost.
However, it does not produce a complete federal funding model.
Therefore, a serious model needs at least five variables:
- Eligibility: Who qualifies under the program?
- Benefit: What does each eligible person or household receive?
- Timing: Is the benefit delivered immediately or over years?
- Financing: Does the government use taxes, appropriations, borrowing, a trust structure, or a combination?
- Administration: What does it cost to verify claims, resolve disputes, prevent fraud, distribute benefits, and oversee the program?
To begin, the first two variables determine the basic scale.
Eligible population × average benefit = gross program cost.
From there, the remaining variables determine how that obligation moves through the federal budget and whether the government can administer it reliably.
That distinction matters. A program can be mathematically simple and institutionally difficult at the same time.
Three Illustrative Reparations Cost Scenarios
Consider three hypothetical models. None is a recommendation or an estimate of what reparations should cost. Instead, these scenarios are sensitivity tests designed to show how quickly the total changes when eligibility and benefit assumptions change.
| Illustrative Model | Eligible Population | Average Benefit | Gross Program Cost |
|---|---|---|---|
| Model A | 10 million | $50,000 | $500 billion |
| Model B | 20 million | $100,000 | $2.0 trillion |
| Model C | 25 million | $150,000 | $3.75 trillion |
Importantly, the lesson is not that one of these numbers is correct.
None of the scenarios claims to be.
Instead, the lesson is that eligibility rules and benefit design control the scale. A small change in either assumption can move the federal obligation by hundreds of billions of dollars.
That means any proposal that announces a total without showing its eligibility and benefit assumptions is withholding part of the model.
The number is an output. The assumptions are the machinery.
A $2 Trillion Program Does Not Have to Spend $2 Trillion at Once
Total program cost gets most of the attention. Yet annual cash flow deserves more.
For example, suppose Model B created a gross obligation of $2 trillion. Paying the entire amount in one fiscal year would create a very different budget event from distributing the same nominal amount across 10, 20, or 30 years.
| Gross Program Cost | 10-Year Schedule | 20-Year Schedule | 30-Year Schedule |
|---|---|---|---|
| $500 billion | $50B/year | $25B/year | $16.7B/year |
| $2.0 trillion | $200B/year | $100B/year | $66.7B/year |
| $3.75 trillion | $375B/year | $187.5B/year | $125B/year |
Still, these figures are simple nominal divisions. They exclude administrative costs, interest expense, inflation adjustments, investment returns, tax effects, and changes in eligibility over time.
That limitation matters.
Even so, the table exposes a distinction that often disappears in political arguments: total program cost and annual federal budget requirement are not the same thing.
Timing changes the fiscal load.
At the same time, it changes the program.
A $100,000 benefit delivered today is not economically identical to the same nominal amount distributed over decades. Inflation changes purchasing power. Delayed payments change when recipients can use the benefit. Financing costs can change the government’s eventual expense.
Consequently, stretching the timeline solves one problem while creating others.
How Could the Federal Government Fund Reparations?
Next, once the obligation is defined, financing becomes the central question.
However, there is no financing mechanism that makes the cost disappear. Each method determines when the cost is recognized, where the burden falls, and which political or fiscal constraint becomes more important.
Five Ways the Financing Structure Can Change
At a high level, the federal government could rely on annual appropriations, dedicated revenue, Treasury borrowing, a capitalized trust, or a hybrid structure. Each approach creates a different relationship among current spending, future obligations, revenue, debt service, and administrative durability.
| Mechanism | Budget Effect | Primary Advantage | Primary Tradeoff |
|---|---|---|---|
| Annual Appropriations | Recurring federal expenditure | Direct and visible | Exposed to repeated budget fights |
| Dedicated Revenue | Pairs spending with a defined revenue source | Makes financing explicit | Creates a concentrated tax and political fight |
| Treasury Borrowing | Adds federal debt and future interest costs | Spreads financing over time | Transfers part of the burden into future budgets |
| Capitalized Trust | Requires upfront or recurring capitalization | Can support long-horizon distribution | Requires governance, funding, and investment rules |
| Hybrid Model | Distributes financing across several channels | Reduces dependence on one mechanism | Adds design and administrative complexity |
In practice, each option changes the ledger differently. The sections below separate those effects.
Annual Appropriations
For example, Congress could authorize payments and fund them through the federal budget. That is straightforward in concept. It is less straightforward politically.
However, if new revenue does not cover the expenditure, the government must accept higher deficits, reduce spending elsewhere, or combine several approaches.
Beyond the initial appropriation, the larger problem is durability. A long-term program tied repeatedly to appropriations could face recurring political pressure.
Dedicated Revenue
Alternatively, Congress could pair the program with a defined revenue source. The specific instrument could take many forms, but the analytical advantage is the same: the funding burden becomes visible.
At the same time, that visibility can become a political constraint.
People can debate a trillion-dollar obligation in the abstract. A dedicated tax identifies who is expected to finance it.
Treasury Borrowing
By contrast, borrowing changes when the government has to raise the money. It does not eliminate the cost.
Moreover, debt creates interest obligations. Those payments compete with future federal priorities and must be included when evaluating the long-term fiscal exposure.
Therefore, the relevant question is not simply whether the United States can issue debt. It can.
The question is what financing structure Congress is willing to carry after the initial legislation is no longer politically new.
A Capitalized Trust
Another option is a trust structure, which could separate program administration from annual individual payment decisions. Congress could capitalize the fund and establish rules for distributions over time.
However, calling something a trust fund does not finance it.
Capitalization still has to come from somewhere.
In addition, the government would need rules governing capitalization, investment, eligible uses, oversight, distributions, and long-term solvency.
A trust changes the architecture. It does not erase the ledger.
Who Actually Bears the Cost?
Moreover, every financing decision creates incidence. Put plainly, somebody carries the burden.
For example, dedicated taxes place more of the burden on the taxpayers or transactions selected by Congress. Spending offsets move the burden toward programs that receive less funding. Borrowing shifts part of the obligation toward future federal budgets through debt service.
Meanwhile, a hybrid model distributes those effects across several channels.
At that point, the political argument becomes more precise.
Accordingly, the relevant question is not whether reparations have a cost. Every major federal program has a cost.
Instead, the relevant questions are who carries it, when they carry it, and what the country chooses not to fund instead.
Those are allocation decisions.
Changing the label on the financing mechanism cannot make those tradeoffs disappear.
What About Inflation?
Inflation is often raised as if any large federal expenditure automatically produces the same result.
That assumption is too simple.
Instead, the inflationary effect of a reparations program would depend on its scale, timing, financing, economic conditions, recipient behavior, and the economy’s ability to supply the goods, services, housing, and assets that additional purchasing power reaches.
For instance, a large immediate cash distribution could create different demand pressure from a phased program. A tax-financed program would interact with aggregate demand differently from a deficit-financed program. Asset-building benefits could also behave differently from unrestricted cash.
None of this means inflation risk should be dismissed.
Rather, inflation has to be modeled instead of merely invoked.
A risk is not an analysis until the mechanism is identified.
The Cost Nobody Sees in the Headline Number
Next comes the part most simple models leave out: administration.
Suppose Congress authorizes a federal reparations program. The legislation still has to become an operating system.
Administrators must establish eligibility standards and receive applications. Records then require authentication, while missing records need a defined process. Contested claims require review, and appeals require adjudication. Meanwhile, payments need controls, fraud attempts require detection, and personal information requires protection.
That means a national program could require:
- eligibility and documentation standards
- genealogical or historical record verification
- claims-processing infrastructure
- identity verification
- appeals and dispute resolution
- fraud prevention
- cybersecurity and data protection
- payment administration
- audits and financial controls
- program oversight
- public reporting
- legal defense and compliance
Those costs should not be treated as footnotes.
Instead, administration is part of the program itself.
A $2 trillion benefit authorization is not a $2 trillion operating system. The government would need enough administrative capacity to process the program without unacceptable breakdown.
At that point, fiscal design becomes institutional design. Consequently, administrative capacity belongs inside the cost model rather than outside it.
Eligibility Is a Fiscal Variable
Likewise, eligibility is often discussed as a political or legal question. Yet it is also one of the largest variables in the budget.
A program based on individual lineage creates one administrative model. A household-based program creates another. Geographic criteria, documentation requirements, age rules, residency standards, and treatment of descendants can all change the eligible population.
Every eligibility rule therefore has two consequences.
First, it determines who receives the benefit.
Second, it changes the cost of the program.
For example, broader rules can increase participation while increasing fiscal exposure and verification risk. Narrow rules can reduce cost while increasing exclusion disputes and appeals.
For that reason, standards matter before distribution begins. The threshold has to be defined before the system can protect it.
Fraud Control Is Not a Side Issue
A national program involving hundreds of billions or trillions of dollars would create substantial incentives for fraud attempts.
Importantly, that observation is not an argument against reparations. It is an operating reality of large payment systems.
Accordingly, the government would need strong identity controls, documentation standards, audit systems, enforcement rules, and an appeals process that can distinguish fraud from legitimate record gaps.
Those controls also require accountability. A system capable of moving large sums of public money needs a way to detect drift, assign responsibility, and correct failures.
The credibility problem is straightforward.
Although a program can survive disagreement, repeated administrative failure can be harder to survive.
The Political Clock Matters Too
Finally, there is another variable the spreadsheet cannot solve: time in government.
For example, a program designed to operate for 20 or 30 years would cross presidential administrations, congressional majorities, budget cycles, lawsuits, economic expansions, recessions, and changes in public opinion.
As a result, durability becomes part of the fiscal model.
Therefore, the program would need rules strong enough to remain dependable through repeated political and administrative pressure. Otherwise, the payment schedule may exist on paper while the institution behind it weakens.
For that reason, a long timeline is not automatically safer than a short one.
Spreading payments lowers annual fiscal pressure.
However, a longer schedule also increases the number of years in which future governments can alter the system.
Ultimately, solving one constraint can expose another.
The Groundwork
Traditionally, reparations are debated as a moral claim, a political demand, or a historical obligation.
Federal implementation would add another dimension to that debate: an operating system.
Such a system requires definitions, standards, financing, administrative capacity, accountability, and enough durability to survive pressure.
Consequently, the questions worth asking become more specific.
Who qualifies? How is the benefit calculated? Then, what is the total obligation? Over what period is it distributed? Which financing method carries it? Finally, what does that financing cost over time? What institution administers the program? How are disputed claims handled? What protects the system from fraud? What happens when political control changes?
Those questions do not resolve the moral case for or against reparations.
Instead, they establish whether a proposal can move from argument to administration.
By itself, a headline number cannot do that.
The arithmetic can tell us the size of the promise. The architecture determines whether the promise can hold.
Continue Building
From National Capacity to Program Cost
America’s Missing Balance Sheet asks what the country owns, owes, maintains, and leaves available for the future. By contrast, this model asks a narrower question: once a proposed federal obligation is defined, what variables determine its scale, annual fiscal load, financing structure, and administrative requirements?
The distinction matters. Specifically, a balance sheet describes financial position and capacity. A funding model describes how a specific policy design would move through budgets and institutions. Neither question, by itself, resolves the underlying political or moral debate.
Permanent Investigation
What Survives When Empire Ends?
Examine institutions, assets, obligations, infrastructure, historical inheritance, and competing approaches to repair.
National Ledger
America’s Missing Balance Sheet
Establish the domestic accounting lens for assets, liabilities, stewardship, and future capacity.
Institutional Inheritance
You Did Not Cause the Harm. What Did the Institution Inherit?
Separate personal culpability from institutional continuity, inherited position, and remedial claims.
Imperial Accounting
The Problem With the Colonial Balance Sheet
Apply a separate accounting method to assets, flows, financiers, payers, users, returns, costs, and what remained.
Remedy Design
What Does Repair Actually Mean After Empire?
Move from documented harm and surviving connection to the separate questions of remedy, recipient, mechanism, objective, and limitation.
Groundwork Architecture
What This Article Is Built On
Core Principle: Accountability Is a Form of Strength
Primary Condition: Accountability
Supporting Condition: Discernment
Governing Mechanism: Eligibility → Benefit → Timing → Financing → Administration
Research Trail
Receipts
The numerical scenarios above are hypothetical sensitivity tests created for this article. They are not federal estimates, recommendations, or claims about the appropriate size of a reparations program. The sources below support the federal budgeting, payment-integrity, eligibility, and institutional-design context used in the analysis.
Federal Budget Analysis
The Congressional Budget Office provides nonpartisan analysis of federal budget and economic issues, including the budgetary effects of proposed legislation and alternative policy designs.
Federal Financing and Debt
Treasury manages federal finances and borrowing. Its fiscal resources provide the institutional background for the article’s distinction between program spending, financing, and debt service.
Eligibility Data and Payment Integrity
GAO reports that federal agencies use more than 100 federal data sources, individually or in combination, to verify recipient eligibility across award and payment processes. GAO has also documented continuing data-quality and interoperability problems.
Improper Payments and Controls
For fiscal year 2025, 15 federal agencies reported an estimated $186 billion in improper payments across 64 programs. The figure illustrates why payment controls, data quality, oversight, and administrative design are material parts of any large federal payment system. Improper payments are not synonymous with fraud.
→ GAO-26-108694, Payment Integrity
→ GAO-26-109100, Combating Fraud in Federally Funded Programs
Groundwork Daily Architecture
→ America’s Missing Balance Sheet
→ What Survives When Empire Ends?
The number is an output. The assumptions are the machinery. The architecture determines whether a proposal can operate as policy.