
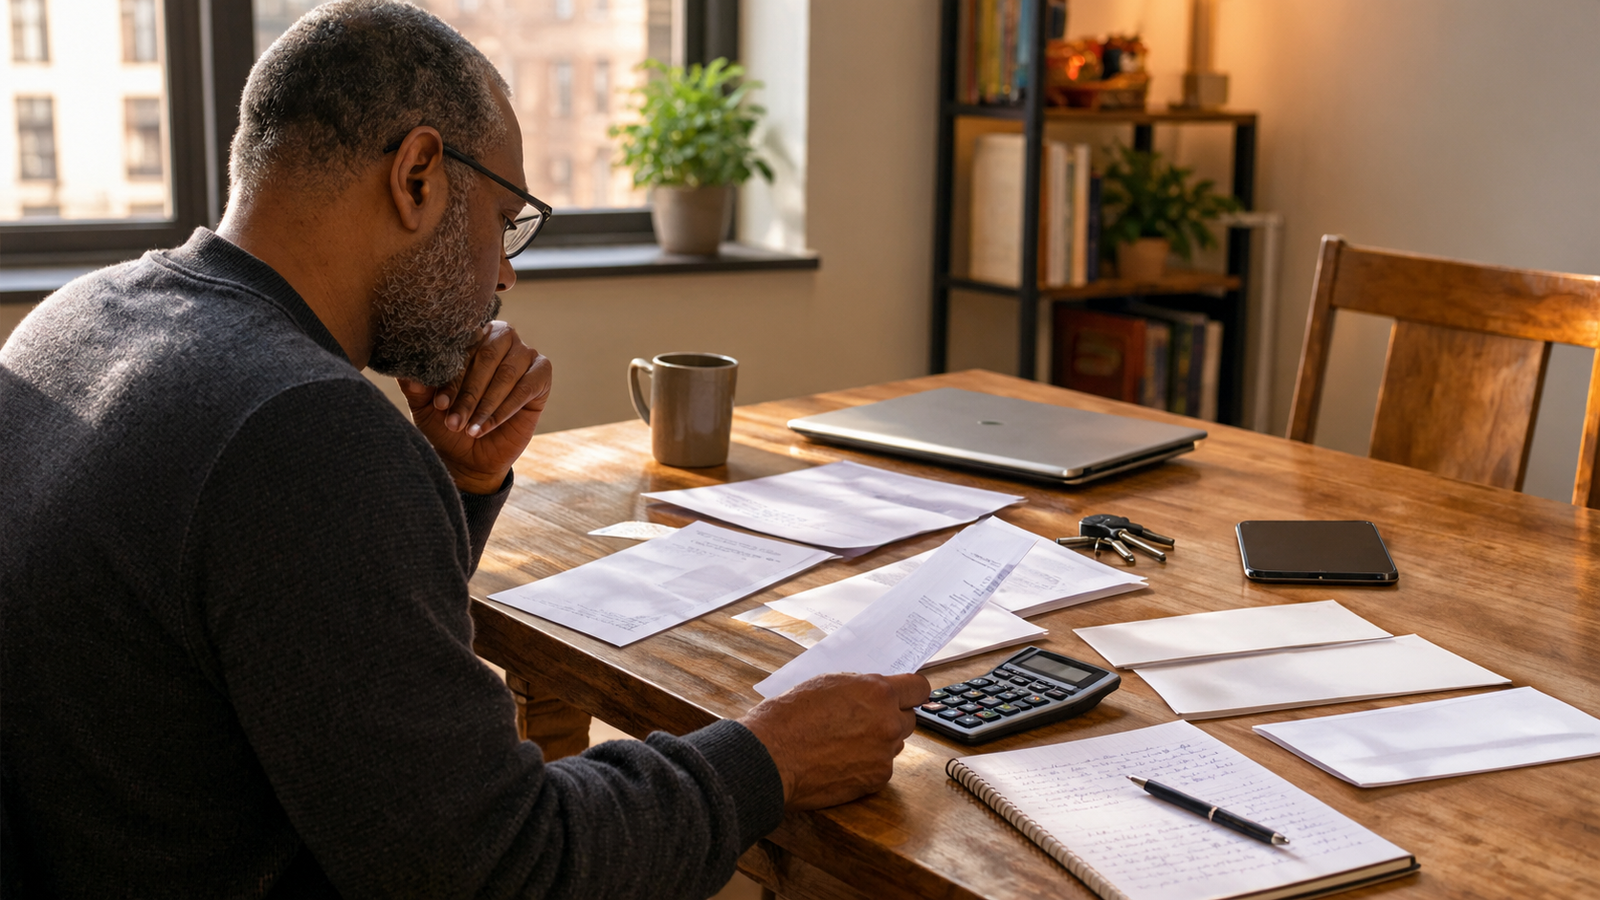
When the paycheck disappears, the obligations remain. What happens next depends, in part, on whether the household has a clear order of priorities.
The rent is still due. The electric bill has a date. The insurance company expects its payment. The car may still need gas, and the refrigerator still needs food. None of those obligations becomes less important because the income that supported them has stopped.
That is what makes an income interruption so difficult. The household loses its usual source of cash, but the calendar continues operating as though nothing changed.
People often respond by trying to pay a little toward everything. The instinct is understandable. Nobody wants to fall behind, and every bill can feel equally urgent when there is not enough money to cover them all.
But equal attention does not produce equal protection. Some missed payments create inconvenience. Others can threaten housing, transportation, essential services, or the ability to return to work.
The immediate task is to understand those differences. When income stops, the household needs a payment priority system.
Start With the Money That Actually Exists
Before deciding which bills to pay, establish how much money is available and when additional money might arrive. This sounds basic, but uncertainty makes it easy to plan around income that has not yet been received.
A final paycheck may be pending. Unemployment benefits may require an application and processing time. A client may owe an invoice. A relative may have offered help. Each possibility matters, but none should be treated as available cash until its timing and reliability are clear.
Start with the current checking and savings balances. Identify any money already committed to transactions that have not cleared. Then list confirmed income expected during the next 30 days.
Keep uncertain money in a separate column. It may eventually improve the situation, but it should not support a payment promise the household cannot keep.
The first question is not how much money the household usually earns. It is how much money can be used safely before the next reliable deposit arrives.
Next, write down every obligation due during that period. Include the amount, due date, available grace period, potential late fee, and consequences of nonpayment. Mark any automatic withdrawals that could reduce the account balance before a deliberate decision is made.
This inventory creates a clearer picture of the problem. It also separates what must happen immediately from what can be negotiated, delayed, reduced, or temporarily discontinued.
What Bills Should Be Paid First When Income Stops?
There is no universal payment order that fits every household. A person who works from a vehicle has different transportation needs from someone who can walk to work. A household with medical equipment that requires electricity faces different utility risks from one without that need.
Still, a useful starting point is to rank expenses by the harm that nonpayment could cause, not simply by the size of the balance or how frequently a creditor calls.
Food, Necessary Medication, and Immediate Safety
Protect essential groceries, necessary prescriptions, and other immediate health or safety needs. Reduce discretionary spending, but do not confuse responsible budgeting with eliminating the necessities that keep people functioning.
Housing and Essential Utilities
Identify what is required to preserve housing and maintain essential services. Rent or mortgage payments, electricity, heating, water, and other necessary utilities deserve close attention. Review actual deadlines, available assistance, and applicable protections before assuming a missed payment will produce an immediate shutoff or loss of housing.
Transportation and the Ability to Earn
Protect the transportation, communications, and work tools necessary to maintain employment or pursue new income. For one person, that means a car payment, required insurance, and fuel. For another, it means transit fare, a working phone, and internet access. The priority depends on what keeps income possible.
Obligations With Serious Legal or Contractual Consequences
Review court-ordered payments, required insurance, secured debts, and other obligations where nonpayment could create significant consequences. These require individual attention because legal requirements, collateral, deadlines, and available remedies vary.
Other Debts and Discretionary Commitments
Credit cards, unsecured loans, subscriptions, memberships, entertainment, and nonessential purchases still matter. However, their payment consequences should be evaluated against the household’s immediate needs. Cancel or pause optional recurring charges where permitted, and contact lenders about hardship options rather than silently ignoring obligations.
These are decision categories, not an instruction to disregard contracts or legal obligations. A household should check the terms of each account and seek qualified assistance when the consequences are unclear.
A credit card reminder might arrive before a utility notice. An automatic subscription may withdraw money without asking. Neither event should determine the household’s priorities.
What matters is the consequence of the payment decision. Will missing this bill endanger housing? Interrupt necessary medical care? Remove transportation needed for work? Trigger the loss of important property? Or create a fee that may be addressed through a hardship arrangement?
Those questions turn a stack of bills into a sequence of decisions.
Make the Difficult Calls Before the Situation Gets Worse
Many people wait until an account is overdue before contacting the company that expects payment. Sometimes embarrassment causes the delay. Sometimes the household hopes another deposit will arrive and make the conversation unnecessary.
Waiting can reduce the options available.
Contact landlords, mortgage servicers, utility providers, insurers, and lenders as early as practical when a payment problem becomes likely. Explain that income has been interrupted and ask what arrangements may be available.
Depending on the provider and circumstances, options might include a payment plan, a revised due date, a hardship program, temporary forbearance, or a referral to assistance resources. None should be assumed or considered approved until confirmed.
Ask Specific Questions
- What happens if the payment cannot be made on the original due date?
- Is there a hardship or temporary payment arrangement?
- Will interest, fees, or additional charges continue?
- How will the arrangement affect the account, coverage, or credit reporting?
- Can the agreed terms be provided in writing?
Keep a record of the date, representative, information provided, and any commitments made. A written record becomes especially important when several providers are involved.
Do not promise a payment date based on money that may never arrive. A smaller arrangement that can actually be honored is more useful than a reassuring promise built on hope.
Build a 30-Day Household Payment Plan
Once the bills have been ranked and the first calls have been made, the household needs a short operating plan. A full annual budget may eventually be necessary, but the immediate concern is the next 30 days.
Begin with four numbers: cash available today, confirmed income expected, essential spending required, and payments that cannot safely be delayed.
Then create a calendar showing when each amount must leave the account. The timing matters. A household may have enough money across an entire month but still face a shortage on the day a major payment is due.
The 30-Day Financial Triage Checklist
- Record available cash and pending withdrawals.
- List confirmed income separately from uncertain income.
- Identify food, medication, housing, utilities, transportation, and other essential needs.
- Rank remaining bills by the consequences of missing payment.
- Review and stop unnecessary recurring expenses where cancellation is permitted.
- Contact providers about hardship arrangements before deadlines whenever possible.
- Put payment dates and confirmed agreements on one calendar.
- Recheck the plan whenever income, expenses, or provider arrangements change.
If the numbers still do not work, acknowledge the remaining gap. A plan that shows a shortage is more useful than one that hides it.
That gap may require additional action: applying for unemployment benefits when eligible, seeking local assistance, negotiating further payment arrangements, or finding temporary income. The appropriate options depend on the household’s circumstances and location.
Do Not Turn a Temporary Interruption Into Permanent Damage
Financial pressure can make expensive borrowing look like the fastest solution. Before taking on new debt, calculate its full cost and determine whether the expected income can realistically support repayment.
A loan that pays this month’s bills but makes next month’s obligations unmanageable has not resolved the underlying shortage.
The same caution applies to draining every available reserve. Some savings may be needed to maintain housing, insurance, transportation, or other essential functions while income is restored.
The objective is to preserve the household’s ability to recover, not simply to make every account appear current for one more week.
Builder’s Note
A household under financial pressure does not need another lecture about discipline. It needs information organized well enough to support a decision.
Put the balances on paper. Put the due dates beside them. Find out what happens when a payment is missed. Then decide what must be protected first.
That process may not create more money. It can, however, prevent limited money from being spent without a clear understanding of the consequences.
When Income Returns, Keep the Payment System
The end of an income interruption does not automatically restore household stability. Deferred payments may come due. Fees may remain. Savings may have been used. Some expenses may have been shifted into the next month.
When income resumes, review the full position before returning to previous spending habits. Confirm the status of each payment arrangement, rebuild essential reserves at a sustainable pace, and decide which recurring expenses still belong in the budget.
Groundwork Daily’s Household Risk Math: Building Protection When the System Is Unstable examines the broader work of preparing for financial instability. This article addresses a different moment: the decisions required after income has already stopped.
A household that survives an interruption should preserve what it learned about its own expenses. Which payments were truly essential? Which obligations could be negotiated? Which costs continued automatically without delivering much value?
Those answers can shape a stronger operating budget long after the immediate pressure has passed.
The Groundwork
Losing income changes the financial choices available to a household. It does not remove the responsibility to make those choices carefully.
Start with verified cash. Identify essential needs. Understand the consequences attached to each bill. Contact providers early. Build a payment calendar around the money that actually exists.
Some households will still face painful tradeoffs. A priority system cannot replace missing wages, erase debt, or guarantee that every essential expense will be covered. It can make the remaining decisions more deliberate and reveal where additional help is necessary.
Financial stability is tested when the usual income is no longer available. The structure built in that moment can protect the household’s ability to recover when the next opportunity arrives.
When you cannot pay everything, know what you are protecting first.
Groundwork Architecture
The governing principle and condition shaping this article.
A clear decision system reduces avoidable confusion when resources are limited.
Income interruption tests which household obligations can be sustained, adjusted, or protected.
Marcus Vaughn
Marcus Vaughn writes about ownership, financial discipline, family structure, and generational continuity. Through Money Monday and Legacy In Motion, he examines the systems that turn income into stability, responsibility into structure, and today’s decisions into tomorrow’s inheritance.
Receipts
The following resources provide practical consumer-finance guidance and assistance pathways relevant to household financial disruption.
- Consumer Financial Protection Bureau, Your Money, Your Goals. Financial education resources addressing cash flow, bill management, debt, and financial decision-making. These materials support the article’s emphasis on assessing available money and prioritizing obligations. Review CFPB resources .
- USA.gov, Government Benefits. A federal starting point for locating information about government assistance programs and eligibility. This resource supports the recommendation to investigate available help when household income is interrupted. Explore assistance information .
- United Way 211. A community resource network that connects people with local assistance options, including help related to housing, utilities, food, and other essential needs. Availability varies by location. Find local resources .