
Economy & Ownership · Cost Transfer
Cost transfer in systems occurs when a decision preserves one benefit by moving part of its expense, risk, labor, time, or disruption somewhere else.
Costs do not disappear because the person making the decision stops seeing them.
For example, a company can reduce payroll expense by leaving positions vacant. A city can protect its current budget by delaying maintenance. Likewise, a business can promise faster service without adding the capacity required to deliver it.
Each decision may improve one visible number.
However, another part of the system now has to absorb what the original decision displaced.
Every Savings Claim Needs a Second Question
First, ask what became cheaper here.
Then ask what became more expensive somewhere else.
Ultimately, that second question is where the real economics begins.
Cost Transfer in Systems Is Not the Same as Cost Reduction
A true cost reduction changes the amount of resources required to produce an outcome.
Better technology, for instance, can reduce labor time. Improved design can lower material waste. Preventive maintenance can also reduce emergency repair.
Those are genuine efficiency gains.
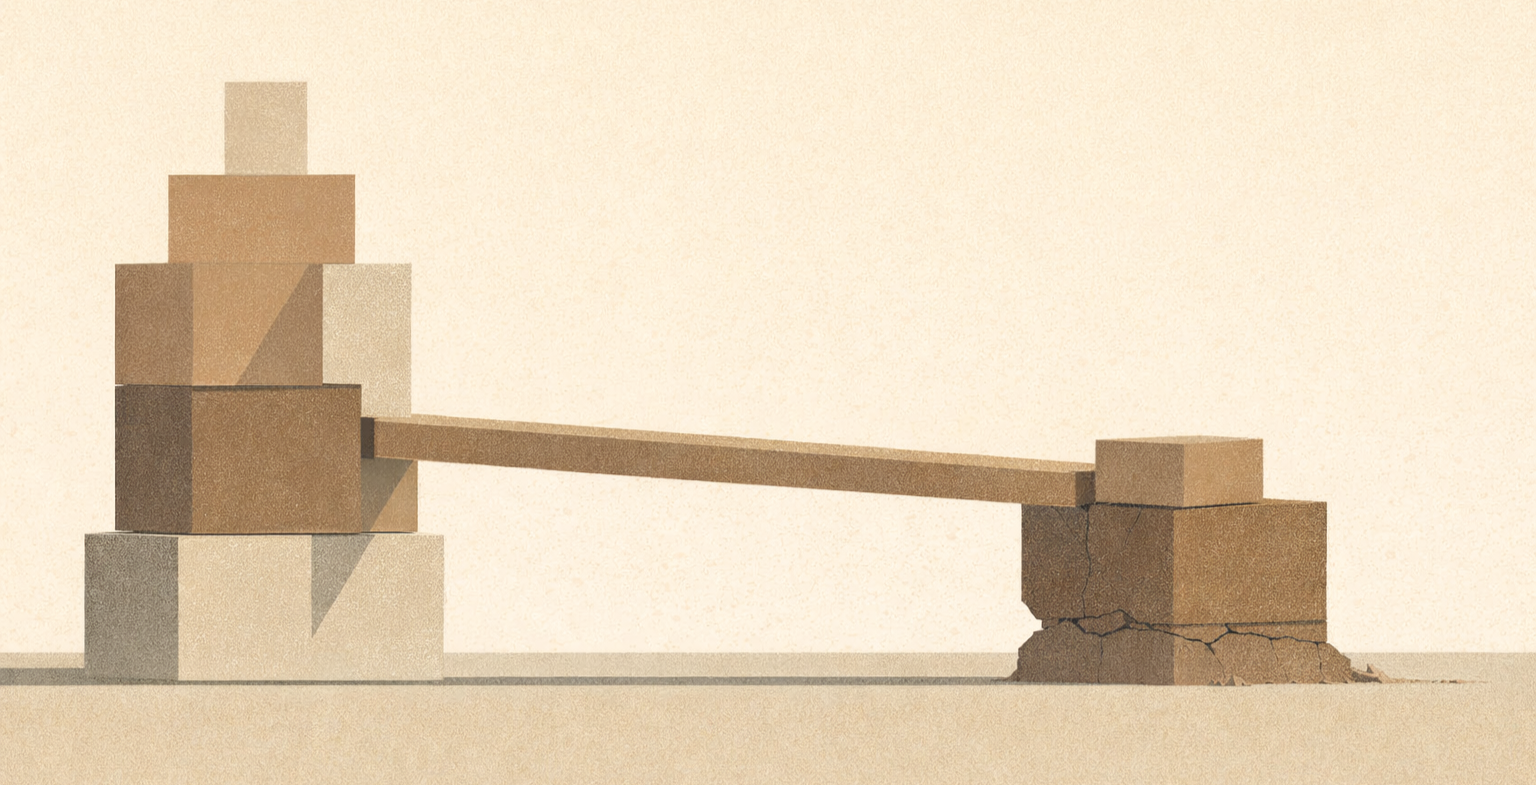
A Transfer Changes the Payer Instead
Cost transfer works differently.
The burden still exists. Instead of disappearing, responsibility for carrying it changes.
Consider a company that reduces scheduled labor while keeping the same service promise.
The labor requirement did not disappear.
Instead, existing workers may work harder, customers may wait longer, or managers may spend more time solving operational failures.
The Ledger Can Improve While the System Gets Worse
This is what makes transfer difficult to see.
The department that initiated the decision may report savings. Meanwhile, another department, person, or future period inherits the expense.
Consequently, local efficiency can create system-wide inefficiency.
Not Every Cost Transfer in Systems Is Exploitative
Cost movement is unavoidable in complex systems.
Insurance transfers risk. Contracts allocate responsibility. Taxes distribute public costs. Businesses also pass some expenses into prices.
None of those arrangements is automatically unjust.
Healthy Transfers Are Visible and Governed
Strong systems identify the cost and name the receiving party.
Moreover, they disclose important tradeoffs and test whether the receiving layer has enough capacity to carry the burden.
Problems begin when the transfer becomes hidden, involuntary, mispriced, or repeatedly pushed toward people with little ability to refuse it.
Consent Does Not Remove Every Power Imbalance
A person may technically accept a cost because the available alternatives are weak.
Therefore, contract language alone cannot settle every economic question.
In practice, power also determines who has meaningful alternatives.
Cost Transfer Usually Follows Leverage
Stronger actors generally have more options.
For example, they can renegotiate, raise prices, change vendors, reduce exposure, delay spending, leave a market, hire specialists, or absorb short-term losses.
By contrast, weaker actors often have fewer escape routes.
The Ability to Refuse Is an Economic Asset
A worker who can leave has more bargaining power than one who cannot.
Similarly, a tenant with several housing options has more leverage than one facing severe scarcity.
A business with multiple suppliers can also negotiate differently from one dependent on a single vendor.
Consequently, cost often travels toward whichever layer has the least practical ability to reject it.
Repetition Can Make the Transfer Look Natural
Once the same group repeatedly absorbs a burden, the arrangement can begin to feel normal.
The worker stays late again. Customers wait again. A family caregiver fills another gap.
Over time, repetition can disguise allocation as inevitability.
The Cost Transfer Chain
Cost transfer in systems becomes easier to analyze when the sequence is mapped from the original decision to the eventual consequence.
Decision
First, someone changes staffing, spending, pricing, policy, maintenance, service, or risk allocation.
Protected Benefit
Next, something important is preserved.
That benefit might be margin, speed, political comfort, cash flow, customer price, schedule, or leadership discretion.
Displaced Cost
However, the protected benefit requires another cost to move.
Receiving Layer
At that point, a worker, customer, supplier, household, asset, public system, or future budget absorbs the displaced burden.
Capacity Loss
Consequently, the receiving layer has less time, money, reliability, flexibility, trust, or resilience available afterward.
Deferred Consequence
Eventually, capacity loss reappears as turnover, failure, higher prices, repair, conflict, reduced quality, or another transfer.
Cost Transfer in Systems Appears Across Economic Life
Businesses
A company may cut labor hours to protect margin.
If productivity does not rise enough to offset the reduction, employees absorb part of the difference through higher workload. Meanwhile, customers may absorb another part through slower service.
Infrastructure
A public authority can delay preventive maintenance to protect the current budget.
Later, residents may pay through delays, unreliable service, property damage, or a more expensive emergency repair.
Housing
A property owner may postpone building investment.
As a result, tenants can carry part of that decision through reduced comfort, reliability, safety, or time spent navigating repairs.
Digital Markets
A platform can lower apparent transaction friction while transferring data, attention, moderation, or service burdens onto users and third parties.
Supply Chains
A powerful buyer may demand lower prices or longer payment terms.
In response, suppliers can reduce margin, delay investment, borrow more working capital, or push pressure farther downstream.
One Cost Transfer Can Create Another
The receiving layer rarely absorbs unlimited burden.
Instead, it may transfer part of the cost again.
Costs Can Cascade Through a System
A supplier facing longer payment terms may extend its own vendor payments.
Meanwhile, a worker facing higher workload may reduce discretionary effort or leave. A city delaying maintenance may eventually require a larger capital program.
Consequently, one transfer can create a chain of secondary transfers.
The Final Payer May Be Far From the Original Decision
This is where simple blame becomes weak analysis.
The person ultimately paying may have no direct relationship with the original decision maker.
Cost can travel through several institutional layers before becoming visible.
The Original Decision Can Disappear From View
By the time failure appears, attention often settles on the layer where the problem finally surfaced.
Therefore, tracing the chain back to its starting point matters.
Discipline Requires Full-Cost Accounting
This is where Discipline Before Dollars enters the argument.
Discipline refuses to count a savings before asking what the savings created elsewhere.
First-Order Savings Can Hide Second-Order Damage
What happens after labor is reduced?
Similarly, what happens after maintenance is delayed or supplier payment terms are extended?
The first-order answer may look attractive.
However, the second-order answer reveals whether the decision actually improved the system.
Full-Cost Accounting Changes Decision Quality
Once hidden costs are included, some apparent savings will still hold.
Others will not.
That distinction is the point.
How to Trace Cost Transfer in Systems
Start with the decision that supposedly created efficiency, stability, savings, or flexibility.
Do Not Stop at the First Ledger
The first budget may show savings.
Elsewhere, the next budget may show overtime. A maintenance ledger may show backlog. Customer data may reveal slower service.
Economic analysis becomes stronger when those ledgers are read together.
Follow the Transfer Until It Stops Moving
If the receiving layer pushes the burden farther downstream, keep tracing.
Otherwise, the analysis ends too early.
Accountability Should Follow the Cost Back to the Decision
Cost transfer becomes dangerous when the people benefiting from the original decision become disconnected from its downstream consequences.
That separation weakens feedback.
Decision Makers Need the Full Price Signal
If leaders see payroll savings but never see turnover, the decision signal is incomplete.
Similarly, if policymakers see deferred capital spending but not resident disruption, the price signal is incomplete.
Buyers can make the same mistake when they see lower supplier prices without seeing supplier fragility.
Therefore, strong accountability reconnects those consequences.
The Goal Is Better Decisions, Not Better Blame
Accountability should not exist merely to assign fault after damage occurs.
More importantly, it should improve the information available before the next decision is made.
Cost Transfer Is the Mechanism Behind the Failure Sequence
This article explains the movement itself.
The next question is what happens when repeated transfers begin eroding the system that receives them.
From Transfer to Failure
When the System Breaks examines how artificial stability turns into capacity erosion and eventual structural failure.
From Failure to Accountability
After failure, When Blame Moves, the Cost Moves With It follows what happens when responsibility begins traveling away from the point of control.
Together, the pieces trace a single economic sequence: cost moves, capacity weakens, the system breaks, and accountability determines who pays next.
Costs Do Not Disappear. They Find a Receiving Layer.
Cost transfer in systems explains why an organization can report improvement while the people or assets around it experience greater strain.
The reported number may be real.
However, it may also be incomplete.
Efficiency Must Be Measured Across the System
A decision that reduces one cost while creating a larger one elsewhere is not necessarily efficient.
Instead, it may only be locally efficient.
Durable systems measure the entire chain.
Follow Who Can Refuse the Cost
Power becomes clearest when two parties face the same burden but only one has the leverage to move it.
Therefore, the central question is not simply who pays.
Ask who had enough power not to.
Follow the Cost Until It Stops Moving
Begin with the decision.
Next, identify the benefit being protected.
Then find the cost that disappeared from the original ledger.
Find the Receiving Layer
Ask who now carries more labor, time, risk, maintenance, financial exposure, or inconvenience.
More importantly, determine whether that person or institution could refuse the transfer.
Price the Second-Order Consequence
Look for capacity loss, turnover, deferred maintenance, slower service, damaged trust, future spending, or another transfer farther downstream.
Reconnect the Decision to Its Full Cost
Finally, return the downstream consequence to the original decision.
That step prevents one ledger from claiming efficiency while another quietly pays for it.
If a savings exists only because another layer is quietly paying the difference, the system did not eliminate the cost. It changed the payer.
Where This Article Sits
This article examines how economic burden moves through systems and why the ability to transfer cost is itself a form of leverage.
Its governing Core Principle is Accountability Is a Form of Strength. Its primary Condition is Discernment, supported by Pressure.
Accountability Is a Form of Strength
Strong accountability reconnects decisions to their full consequences.
When cost moves away from the original decision, accountability prevents the decision maker from seeing only the benefit while another layer absorbs the price.
Discernment
Discernment distinguishes genuine efficiency from cost displacement.
Specifically, it asks whether a reported savings reflects lower resource use or merely a burden that became less visible after moving somewhere else.
Explore the Full Groundwork Architecture
Core Principles:Structure Builds Freedom · Stillness Is Strategy · Discipline Is Emotional Governance · Structure Is Mercy · Discipline Before Dollars · Accountability Is a Form of Strength · Build What Holds
Conditions:Capacity · Discernment · Alignment · Pressure · Overload · Recovery · Clear
Browse the complete Groundwork Daily Core Principles and The Conditions architecture.
Meet the Builder
Samual Drayton
Samual Drayton examines the structure beneath economic activity: who owns the asset, who controls access, who sets the terms, who absorbs risk, and where cost finally settles after money moves.
His work follows ownership, pricing, leverage, institutions, markets, incentives, financial systems, and capital retention to reveal the difference between visible price and full economic cost.
Signature philosophy: Follow the money past the transaction. The structure tells you who controls the terms, who carries the cost, and where the value settles.
Sources & Supporting Evidence
- U.S. Government Accountability Office. Standards for Internal Control in the Federal Government. The Green Book provides a framework for identifying risk, assigning responsibility, establishing controls, monitoring performance, and correcting weaknesses before they compound. Review the GAO Green Book .
- Occupational Safety and Health Administration. Recommended Practices for Safety and Health Programs. OSHA emphasizes management leadership, worker participation, hazard identification, prevention, and continuous improvement rather than transferring preventable operating risk onto workers. Review OSHA guidance .
- National Institute for Occupational Safety and Health. Stress and Work. NIOSH provides evidence on how excessive demands, organizational conditions, available resources, and work design can move operational strain into worker health and capacity. Review NIOSH material .
- Groundwork Daily. When the System Breaks. Companion analysis examining how repeated cost transfer creates artificial stability, capacity erosion, normalized degradation, and eventual failure. Read the article .
- Groundwork Daily. When Blame Moves, the Cost Moves With It. Companion analysis tracing how responsibility and consequence can separate after a system fails. Read the article .
- Groundwork Daily. Accountability Is a Form of Strength. The governing Core Principle for this article’s argument that decision makers should remain connected to the consequences generated by the systems they control. Explore Accountability Is a Form of Strength .
- Groundwork Daily. Discernment. The governing Condition for distinguishing true efficiency from costs that have merely become less visible after moving somewhere else. Explore Discernment .