
Economy & Ownership · Capital Circulation
Capital circulation explains why money can enter a neighborhood every day and still fail to build lasting wealth there. Economic activity matters, but the decisive question is what remains after wages, rent, debt, suppliers, fees, and ownership claims are paid.
A neighborhood can look economically alive.
Stores open, restaurants serve customers, workers receive paychecks, and contractors complete jobs. Meanwhile, churches, schools, salons, clinics, grocery stores, barbershops, and small businesses remain active.
From the sidewalk, therefore, the economy appears to be moving.
Yet movement is not the same as accumulation.
Money Can Pass Through Without Becoming Wealth
Income may arrive through wages, benefits, customers, contracts, events, tourism, public spending, and business revenue.
Soon afterward, however, much of that money can leave again through rent, debt service, insurance, suppliers, franchise payments, platform fees, utilities, taxes, lenders, and ownership structures located somewhere else.
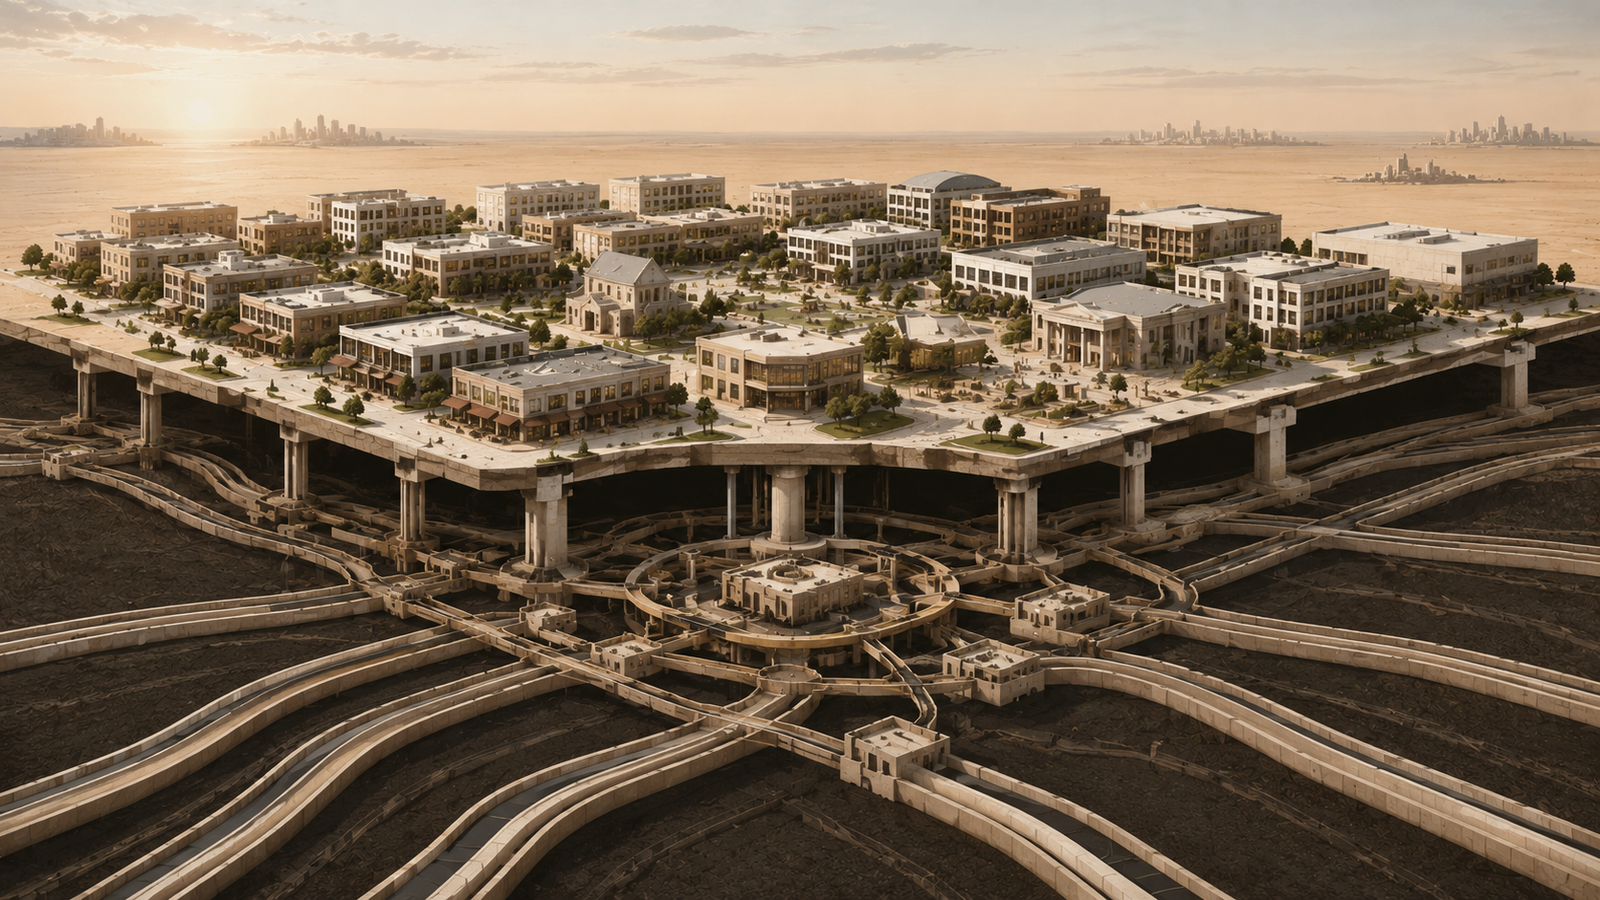
In that kind of system, the neighborhood operates more like a corridor than a reservoir.
Money enters, performs a transaction, and then exits.
Importantly, that pattern does not require conspiracy. Structure is enough.
What Capital Circulation Actually Means
Capital circulation describes how money, credit, assets, investment, and economic value move through a system.
The concept reaches beyond cash changing hands because every transaction creates another question: where does the money go next?
The First Transaction Is Only the Beginning
For example, a dollar spent at a local business may support payroll, inventory, rent, taxes, debt service, technology, and profit.
Therefore, the fact that the original transaction happened locally tells us very little about where the value ultimately settles.
A supplier may receive part of the dollar, while a landlord receives another share. In addition, a bank, insurer, payment processor, software company, franchise owner, or outside equity holder may capture still more.
As a result, local demand can begin the transaction without capturing most of its downstream value.
Economic Motion Has to Become Capacity
Every economy has motion. The more useful question, however, is whether some of that motion becomes reserves, business equity, property, productive assets, professional capacity, institutional strength, or future investment.
If nothing durable remains, the money circulated without producing much local position.
This article therefore extends the argument in Buying Power Without Ownership Is Not Wealth .
Buying power can influence where money enters the system. Capital circulation explains what happens after it enters.
Income Is Not the Same as Capital
Income is money received through wages, business activity, benefits, distributions, or other sources.
Capital, by contrast, is value capable of supporting future production, ownership, investment, or economic capacity.
That distinction changes how a neighborhood economy should be read.
Income Can Be High While Capital Formation Remains Weak
A worker can earn wages while holding little savings, property, equity, or investment capacity.
Similarly, a household can receive substantial income while most of it immediately returns to housing, debt, food, transportation, insurance, taxes, utilities, and other obligations.
At the neighborhood level, the same pattern can appear at scale.
Residents work, businesses sell, and money moves continuously. Nevertheless, the local asset base may remain thin.
Income Supports Life Before It Supports Wealth
None of this makes income unimportant.
Income pays for food, shelter, transportation, education, health, caregiving, repairs, and ordinary participation in economic life.
The problem emerges when nearly all income is consumed by obligations before enough value can become savings, equity, property, business assets, or investment.
Capital Formation Is the Next Economic Threshold
A durable local economy therefore needs more than income entering households.
Eventually, some portion of economic activity must become assets capable of producing or preserving future value.
Capital Leakage Is Usually Quiet
Capital leakage occurs when money leaves a local economic system before enough of its value can reinforce local ownership or productive capacity.
Rather than one dramatic event, leakage usually happens transaction by transaction.
Rent
Households and businesses pay for space. When the asset is owned elsewhere, the rent stream builds value somewhere else.
Debt Service
Borrowers pay interest and fees to lenders. Although those payments can finance ownership, they can also move value outward when financing relationships remain external.
Inventory and Inputs
Local businesses often purchase goods, equipment, technology, and services from firms outside the neighborhood.
Fees and Intermediation
Delivery services, payment processors, software platforms, franchises, and other intermediaries can capture part of the margin before the local firm retains it.
Leakage Does Not Require Bad Intent
A grocery chain can operate normally while its profits settle somewhere else.
Likewise, a tenant can pay an ordinary lease, a borrower can honor a legitimate loan, and a business can pay a necessary supplier.
In other words, nothing about those transactions requires exploitation to produce outward capital movement.
Structure alone can create the pattern.
Consumer Blame Misses the Mechanism
The weak version of this conversation treats capital leakage as a failure of individual shoppers.
Consumer decisions matter. However, they cannot explain ownership of buildings, availability of financing, supplier networks, institutional capacity, or control of productive assets.
When those deeper layers sit elsewhere, money already has established paths outward.
A Busy Neighborhood Can Still Be Economically Exposed
Activity measures movement, while ownership measures position.
Confusing those two measurements makes commercially active neighborhoods look economically stronger than they may actually be.
Crowds Do Not Tell You Who Owns the Asset
Packed stores, full restaurants, event traffic, active sidewalks, and visible consumer spending can all be evidence of strong demand.
Yet demand does not tell us who owns the property, who finances the businesses, where suppliers are located, who holds company equity, or who benefits when local property values rise.
Those questions belong to a different layer of the economy.
Groundwork Daily examines that layer directly in Who Owns the Neighborhood?
Cultural Importance and Economic Control Are Different
A neighborhood can be culturally essential, commercially valuable, and socially connected while having limited control over the assets that determine its future.
Rather than a contradiction, that is what economic activity looks like when ownership remains somewhere else.
Ownership Changes the Destination of the Money
Ownership matters because it changes what can remain after the transaction.
Business Ownership Can Retain Margin
When an operating business is locally owned, profits, retained earnings, customer relationships, brand value, equipment, and future enterprise value have a greater chance of remaining connected to local decision-making.
Still, ownership does not guarantee success.
A poorly operated local business can destroy value just as easily as any other weak enterprise.
Ownership creates the possibility of retention, not immunity from standards.
Property Ownership Can Retain the Rent Stream
When buildings are locally owned, rent can become income, equity, maintenance capacity, collateral, or reinvestment for the owner rather than a permanent outward payment.
Again, local ownership alone is not enough because competence, stewardship, fair dealing, and governance still matter.
Ownership Is a Power Question
The stronger questions are therefore structural.
Who owns the asset, and who captures the margin? Which party controls the terms, and which one carries the downside? Ultimately, who benefits when the neighborhood becomes more valuable?
Together, those questions reveal whether a place is building wealth or mainly hosting transactions.
Rent Can Turn Local Success Into Outside Value
For instance, housing and commercial space are recurring costs. Consequently, property ownership sits near the center of capital circulation.
Every month, households and businesses pay for access to space, while the economic effect depends partly on who owns the underlying asset.
A Successful Business Can Still Be Vulnerable
A restaurant may build demand, create jobs, strengthen a commercial corridor, and become culturally important.
Yet if the company does not control its space, the success of that very corridor can eventually create pressure through higher occupancy costs or changing lease terms.
In that case, the operating company created some of the value, while the property structure determines who can capture another part of it.
Ownership Changes the Operating Position
Even so, a business that owns its building still faces taxes, insurance, repairs, debt, maintenance, and market risk.
Nevertheless, the strategic position changes because the company now holds an asset rather than only paying for access to one.
A neighborhood can therefore become more valuable without becoming more secure when rising economic value is disconnected from local property ownership.
Debt Can Build Ownership or Drain Capacity
Debt is not inherently an economic leak.
Used well, borrowing can help a household acquire property, allow a business to buy equipment, or enable an institution to finance expansion.
In those cases, debt supports asset formation.
Terms Determine Whether Financing Helps
The economic question is not simply whether debt exists.
Instead, interest rates, fees, repayment schedules, collateral requirements, guarantees, maturity, and cash-flow pressure all affect whether financing strengthens or weakens the borrower.
Poor terms can consume the margin that might otherwise have become retained earnings or future investment.
Financial Institutions Shape Capital Circulation
Banks, credit unions, CDFIs, investment funds, and other lenders determine how deposits and capital become financing.
Where those relationships are weak, borrowers may have fewer choices, less negotiating leverage, or less access to financing appropriate for the economic job they are trying to perform.
Consequently, financial infrastructure belongs inside any serious discussion of local value retention.
A Local Economy Needs More Than Local Spending
Naturally, buying nearby can create useful demand.
However, local spending becomes more economically durable when it connects to businesses, suppliers, property, financing, institutions, and skill systems that can retain part of the resulting value.
Support and Capacity Are Different
A business with strong customer support can still struggle with weak margins, poor bookkeeping, inadequate working capital, unstable leases, limited supplier access, or founder dependence.
Consumer demand may help the company survive. Operating systems, by contrast, determine whether it can become stronger.
Ask What the Spending Can Become
The practical question is therefore not only where residents spend.
Instead, the stronger question is what structures allow spending to become payroll, retained earnings, assets, management capacity, equity, property, and reinvestment.
That shift moves the conversation from consumer morality into economic design.
Supply Chains Decide How Much Revenue Can Stay
In fact, retail businesses are only the visible end of a larger system.
Behind them sit wholesalers, distributors, manufacturers, logistics firms, payment systems, landlords, software vendors, lenders, insurers, and other suppliers.
Weak Supplier Terms Reduce Retention
A business that buys at poor wholesale rates may have less margin to retain.
Likewise, inadequate storage can prevent efficient purchasing, while weak credit terms can create additional cash-flow pressure.
Limited distributor access may also make it harder for smaller firms to compete on selection or price.
Groundwork Daily examines that upstream structure in The Hidden Economy Behind Every Store .
Retention Can Improve Through Shared Infrastructure
Better wholesale relationships, shared logistics, cooperative purchasing, storage capacity, technology, local production, or stronger procurement relationships can improve the economics available to local firms.
Without those capabilities, consumer spending can arrive locally while supplier payments quickly carry much of it elsewhere.
Institutions Turn Capital Circulation Into Something Repeatable
Ultimately, without institutions, economic activity remains fragmented.
A customer buys from a business, the business pays suppliers, a tenant pays rent, and a borrower pays a lender.
Each transaction can be rational on its own. Collectively, however, the system may remain weak at retaining value.
Institutions Can Recycle Economic Capacity
A credit union can turn deposits into loans.
Meanwhile, a community development organization can acquire and manage property, while a land trust can preserve a different form of control over land.
Merchant organizations can address shared operating problems. In addition, business-development institutions can improve technical capacity, and investment vehicles can pool resources for larger economic tasks.
Different institutions perform different jobs.
Institutions Need Governance Too
Institutions are not automatically effective because their mission sounds good.
They still need standards, competent management, financial controls, accountability, succession, and measurable performance.
Nevertheless, without durable containers, capital circulation remains dependent on isolated transactions and individual relationships.
That is why Building an Ownership Economy That Lasts places institutional capacity at the center of durable ownership.
Community Investment Can Convert Activity Into Capacity
In short, community investment is broader than charity.
Depending on the structure, it may include business lending, property acquisition, home repair financing, workforce development, startup capital, supplier infrastructure, local procurement, technical assistance, or investment vehicles.
The Goal Is Not Economic Isolation
No healthy neighborhood keeps every dollar inside its boundaries.
Local economies trade with regional, national, and global economies because outside exchange can provide goods, capital, technology, talent, customers, and expertise that are not available locally.
Isolation is therefore not the objective.
The objective is stronger exchange from a stronger ownership position.
The Better Measure Is What the Money Strengthened
Before money leaves, ask what it strengthened.
For instance, did it support wages, create retained earnings, or help a business acquire an asset? Just as importantly, did it deepen professional skill, strengthen an institution, or improve local ownership?
Those questions reveal whether circulation produced more capacity before the value moved elsewhere.
Trust Changes the Cost of Capital Circulation
Above all, trust affects how quickly people can form partnerships, share information, lend, refer, invest, buy, and solve problems.
Consequently, low-trust environments become more expensive.
More time and documentation may be required because everyone is protecting against uncertainty.
Trust Is Built Through Repeated Performance
Reliable businesses keep agreements, communicate capacity honestly, maintain records, correct mistakes, and pay obligations when promised.
Institutions, meanwhile, build trust through transparency and consistent standards.
Investors contribute by honoring terms and avoiding opportunistic behavior when circumstances change.
None of that is sentimental. Instead, it reduces friction.
Groundwork Daily examines the mechanism more directly in The Business of Trust .
The Local Value Retention Chain
The movement from economic activity to durable local wealth becomes easier to understand when the process is separated into stages.
The Local Value Retention Chain identifies where value can either strengthen the local system or leave it.
Income
First, money enters households, businesses, institutions, or organizations through wages, revenue, benefits, contracts, investment, or other sources.
Spending
Next, households and organizations use that income to purchase goods, services, housing, transportation, financing, insurance, technology, and other necessities.
Local Capture
From there, some portion of that spending reaches locally connected businesses, workers, property owners, suppliers, or institutions.
Leakage
Afterward, value can exit through outside suppliers, landlords, lenders, platforms, taxes, fees, franchises, insurance, and other claims on the transaction.
Retention
What remains after those obligations determines whether the transaction leaves behind profit, reserves, savings, equity, knowledge, or operating capacity.
Asset Formation
Retained value can then become property, equipment, financial assets, intellectual property, business equity, technology, reserves, or other productive assets.
Reinvestment
In turn, assets and retained earnings can finance another round of hiring, business growth, acquisitions, lending, property, training, or investment.
Institutional Capacity
Eventually, when enough value is repeatedly retained and governed, institutions begin to hold knowledge, assets, relationships, standards, and capital beyond one transaction or one individual.
Local Wealth Retention Starts With a System Map
Before a neighborhood can improve capital retention, it has to understand where value currently moves.
Otherwise, economic strategy becomes guesswork.
Map the Entry Points
Start by asking where household income comes from.
Which industries employ residents? Which public contracts, institutions, visitors, or businesses bring outside money into the area?
Map the Exit Points
Next, identify where residents spend and who owns the commercial property.
Which suppliers serve local firms? From there, ask which lenders finance households and businesses, and which platforms or franchises collect recurring fees.
Map the Retention Points
Finally, identify which businesses own productive assets, which institutions hold property, and which companies retain earnings.
Where does local investment already occur? Which firms could expand if a specific bottleneck were removed?
Practical Capital Retention Is Usually Unglamorous
Once the system is visible, the right intervention depends on where value is being lost.
Improve Financial Visibility
Stronger bookkeeping, pricing, cash-flow forecasting, tax planning, and operating controls can help businesses understand what they actually retain.
Strengthen Property Position
Lease education, acquisition strategy, land stewardship, commercial-property ownership, and long-term occupancy planning can reduce exposure to displacement.
Improve Supplier Economics
Shared purchasing, stronger vendor relationships, storage, logistics, procurement capacity, and local production can improve the amount of revenue businesses retain.
Build Better Financial Pathways
Credit relationships, CDFIs, loan funds, investment vehicles, guarantees, and technical assistance can improve how capital reaches viable businesses and assets.
Administrative Work Is Economic Development
Bookkeeping can be economic development.
Lease review can also be economic development, just as supplier access, lending infrastructure, succession planning, and governance can be.
These interventions receive less attention than public campaigns because much of the work is administrative.
That is not a weakness. In practice, it is often where retention is actually built.
Symbolic Capital Circulation Is Not an Economic Strategy
Admittedly, telling people to “keep the dollar in the community” can create useful attention.
Yet the phrase becomes weak when nobody explains which structures are supposed to keep the value.
Spending Cannot Create Missing Infrastructure by Itself
Consumer loyalty cannot manufacture commercial-property ownership, create supplier networks, build financial institutions, repair bookkeeping, or design investment vehicles merely through repetition.
Those systems have to be constructed.
Pride may motivate the work. Infrastructure, however, is what allows the work to hold.
The Language Has to Mature
A stronger economic conversation therefore moves beyond whether people support local businesses.
Instead, it asks whether that support reaches firms capable of retaining value and whether institutions exist to convert some of that retained value into future ownership.
Why Money Leaves the Neighborhood So Quickly
In short, money leaves quickly when the local economy contains more payment obligations than ownership positions.
Residents may rent rather than own. Meanwhile, businesses may lease from outside property owners, while suppliers, lenders, platforms, franchises, and insurers capture portions of local revenue.
Under those conditions, the exit routes are already built.
The Goal Is Not to Eliminate Outflow
Every functioning economy sends money outward.
Businesses import goods, households purchase services elsewhere, institutions borrow from outside lenders, and investors allocate capital across markets.
Healthy economic systems exchange.
The important distinction is whether that outward exchange occurs after enough value has been retained to strengthen the local asset base.
Stronger Economies Trade From a Stronger Position
A neighborhood with more property ownership, better-capitalized businesses, stronger financial relationships, productive institutions, skilled operators, and investable assets can participate in outside markets without every transaction weakening its internal position.
Therefore, building a stronger position is more useful than attempting to keep every dollar inside.
Capital Circulation Connects Buying Power to Group Economics
This article occupies a specific position in the second Power & Price arc.
First: Buying Power
Buying Power Without Ownership Is Not Wealth establishes that consumer spending cannot substitute for asset ownership.
Second: Market Architecture
Next, The Rules Were Written Before We Entered the Market examines how policy and institutions shape the market before the transaction begins.
Third: Capital Circulation
This article then follows the money after it enters the neighborhood and identifies the mechanisms through which value can leave before durable ownership forms.
Fourth: Group Economics
Finally, Group Economics Begins With Ownership, Not Spending asks how coordinated economic activity becomes ownership, capital, institutions, and continuity.
Capital Circulation Determines What the Activity Leaves Behind
In the end, a neighborhood can be economically active and still remain economically exposed.
It can have wages without much capital formation, spending without much ownership, thriving businesses without property control, and rising commercial value without durable local equity.
That happens when the receiving system has too few places for value to remain.
The Answer Is Not Guilt or Isolation
Consumers should not be blamed for every structural weakness in the economy around them.
Likewise, neighborhoods should not attempt to cut themselves off from outside trade, financing, suppliers, customers, or institutions.
The stronger answer is structural.
Build More Places for Value to Land
More business equity can create one retention point.
Property ownership creates another. Meanwhile, stronger suppliers, better financing, skilled professionals, governed institutions, and reinvestment create still more.
None of those systems eliminates capital leakage.
Together, however, they can change what the neighborhood owns before the money leaves.
Build Something the Money Can Strengthen Before It Leaves
Money will move. The economic objective is not to stop that movement.
Instead, the objective is to build enough ownership, operating capacity, financial infrastructure, property control, supplier strength, professional expertise, and institutional memory that the movement leaves something durable behind.
Retention Has to Become an Operating Capability
Strong capital circulation creates more than transactions.
It allows income to become retained value, retained value to become assets, and assets to support another round of investment.
Over time, that cycle can create institutions capable of carrying economic strength beyond the original customer, founder, or transaction.
Money entering the neighborhood is activity. What remains after it moves is the beginning of economic power.
Where This Article Sits
This article examines whether an economic system has enough structure to retain productive value before money exits through ordinary obligations and external ownership.
Its governing question is not whether money leaves. Money will always leave. Instead, the question is whether enough capacity exists to convert economic activity into assets, ownership, reinvestment, and institutional strength before it does.
Build What Holds
Economic activity becomes more durable when structures exist to hold part of the value created through demand, labor, enterprise, property, and investment.
Without those containers, money can move continuously while durable position remains thin.
Capacity
Capacity determines whether households, businesses, property systems, professional networks, and institutions can retain, govern, and reinvest enough value to strengthen the next economic cycle.
Without capacity, local demand can remain strong while the underlying ownership position stays fragile.
Explore the Full Groundwork Architecture
Core Principles: Structure Builds Freedom · Stillness Is Strategy · Discipline Is Emotional Governance · Structure Is Mercy · Discipline Before Dollars · Accountability Is a Form of Strength · Build What Holds
Conditions: Capacity · Discernment · Alignment · Pressure · Overload · Recovery · Clear
Browse the complete Core Principles architecture and Conditions architecture .
Meet the Builder
Samual Drayton
Samual Drayton examines the structure beneath economic activity: who owns the asset, who controls access, who sets the terms, who absorbs the cost, and where value remains after money moves.
Through Power & Price, he follows pricing, leverage, markets, institutions, supply systems, ownership, and capital retention to reveal the difference between economic activity and durable economic position.
Signature philosophy: Follow the money past the transaction. The structure tells you who controls the terms, who carries the cost, and where the value settles.
Overall, expect practical Groundwork on economic power, ownership, pricing, leverage, market structure, cost transfer, institutions, supply systems, trust, community wealth, and capital retention.
Sources & Further Reading
-
U.S. Treasury · Community Capital
U.S. Department of the Treasury, Community Development Financial Institutions Fund. Federal programs and institutional resources supporting CDFIs, community-development lending, investment capacity, and access to capital in underserved markets. Review the CDFI Fund . -
Federal Reserve · Community Development
Federal Reserve Bank of San Francisco. Community Development research and resources examining economic opportunity, financial access, housing, small-business conditions, and community investment. Review Community Development research . -
U.S. Census Bureau · Business Ownership
U.S. Census Bureau. Annual Business Survey. Federal data on employer businesses, receipts, payroll, employment, owner demographics, and characteristics of business ownership. Review the Annual Business Survey . -
U.S. Economic Development Administration · Economic Capacity
U.S. Economic Development Administration. Programs supporting regional economic development, business ecosystems, infrastructure, planning, and economic resilience. Review the Economic Development Administration . -
U.S. Small Business Administration · Operating Capacity
U.S. Small Business Administration. Manage Your Business. Guidance covering financial management, hiring, taxes, compliance, business operations, growth, and organizational capacity. Review SBA business-management resources . -
Groundwork Daily · Buying Power
Groundwork Daily. Buying Power Without Ownership Is Not Wealth. Companion Power & Price analysis examining the difference between consumer demand and durable asset ownership. Read the article . -
Groundwork Daily · Market Architecture
Groundwork Daily. The Rules Were Written Before We Entered the Market. Companion analysis examining public policy, property systems, institutions, education, infrastructure, and the rules surrounding economic opportunity. Read the article . -
Groundwork Daily · Upstream Supply Systems
Groundwork Daily. The Hidden Economy Behind Every Store. Companion analysis examining suppliers, distribution, wholesale access, margins, and the systems behind the visible retail transaction. Read the article . -
Groundwork Daily · Property Ownership
Groundwork Daily. Who Owns the Neighborhood? Companion analysis examining land, buildings, leases, lenders, property control, and where neighborhood economic value settles. Read the article . -
Groundwork Daily · Trust
Groundwork Daily. The Business of Trust. Companion analysis examining trust as economic infrastructure that lowers friction and supports repeated cooperation. Read the article . -
Groundwork Daily · Ownership Economy
Groundwork Daily. Building an Ownership Economy That Lasts. Companion analysis connecting assets, institutions, suppliers, governance, trust, and economic continuity. Read the article . -
Groundwork Daily · Group Economics
Groundwork Daily. Group Economics Begins With Ownership, Not Spending. The next article in the Power & Price arc, examining how coordinated economic activity becomes ownership, organized capital, institutions, and durable capacity. Read the article .